

One year of accounts can provide a useful record of a business’s first trading period. It does not answer every question a mortgage lender asks about income or establish that the available history meets every lender’s requirements.
The practical starting point is what “one year” means in your case: when trading began, the period the accounts cover and whether they are final. A clear timeline is more useful than assuming all short-history applications are treated alike.
One set of accounts can cover different periods
The following examples are fictional. They explain dates rather than eligibility or a lender’s accepted income calculation.
| Record | Illustrative dates | What it establishes | What remains separate |
|---|---|---|---|
| Business starts trading | 1 January 2025 | The stated trading start, subject to supporting records. | An incorporation date alone does not necessarily identify this date. |
| First completed accounts | 1 January to 31 August 2025 | Results for eight months. | One set of accounts does not make this a twelve-month period. |
| Subsequent trading records | 1 September 2025 to 31 March 2026 | Information about seven later months. | Later receipts are not automatically added to or annualised with earlier profit. |
| Personal tax year | 6 April 2025 to 5 April 2026 | A different date boundary from those accounts. | The lender decides the required tax documents and how relevant figures are reconciled. |
HMRC explains the tax-year dates and how to obtain tax calculations and overviews in its SA302 guidance. An SA302 and a tax year overview are separate records; the requested years and acceptable format should be confirmed for the case.
Published lender examples: why one year is not a universal rule
Policy examples checked 2 November 2026. These are limited illustrations of published criteria, not an exhaustive comparison, product recommendation or confirmation that either lender will accept an application. Check the full current policy and relevant product before relying on it.
| Lender and primary source | What its published information says | Important limit |
|---|---|---|
| Nationwide: self-employment income | Its standard evidence route refers to two years of tax calculations and matching overviews, or an accountant’s certificate detailing two years of accounts. | The same page describes specific shorter-history circumstances. They are not a general one-year rule. |
| Kensington: self-employed mortgages | Its published page describes one year’s trading history up to 85% loan-to-value and use of the latest year’s accounts. | This headline does not replace full criteria, document requirements, affordability, credit and property assessment. |
Match each document to the question it answers
| Question | Records that may help | Avoid this mistake |
|---|---|---|
| When did the activity begin? | Trading-start information and dated business records. | Using a company-registration date as the only trading evidence. |
| What period has been completed? | Final accounts with their start and end dates. | Calling eight months a full year or presenting a draft as final. |
| Which income belongs to the applicant? | Business-structure, ownership, tax and remuneration records as requested. | Adding turnover, profit, salary and dividends together without the lender’s method. |
| What happened after the year end? | Requested recent statements or current trading information. | Treating every bank receipt as extra annual mortgage income. |
| Did the structure change? | Records linking the earlier activity to the new structure. | Counting overlapping periods twice or assuming continuity is automatically accepted. |
For example, a business’s £60,000 sales, £35,000 costs and £25,000 profit are three descriptions of the same trading period, not £120,000 to add together. Drawings or transfers to the owner need to be understood within the business structure; they do not automatically create additional profit. This arithmetic example does not specify which figure a lender will accept.
One year of accounts: Establish the actual trading period
Visual explanation: one year accounts
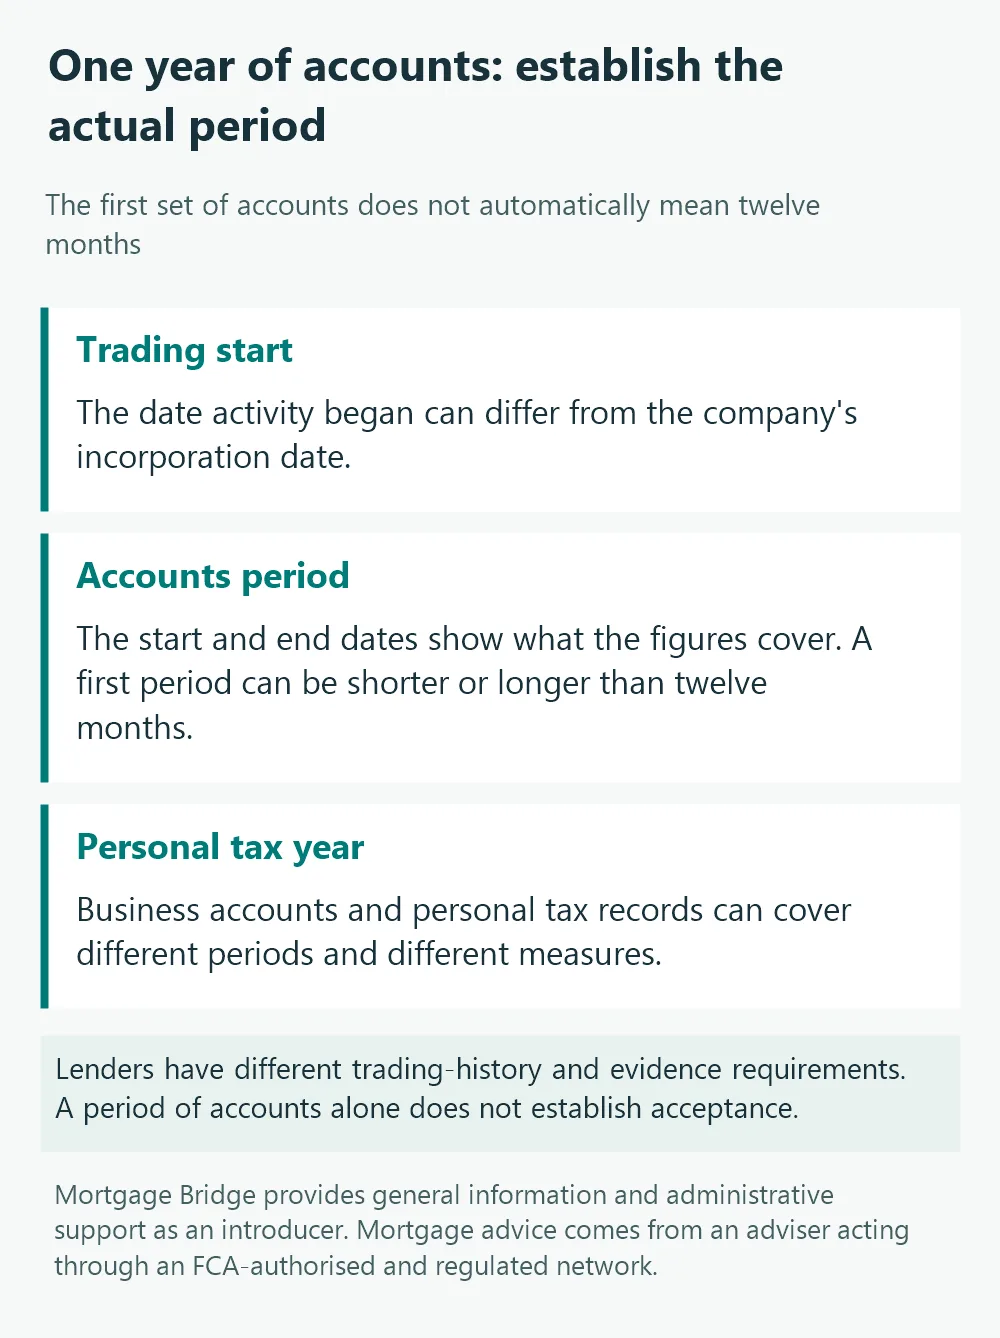
Record the date the business began trading and the start and end dates of the accounts. The date a company was incorporated is not necessarily the date its activity began.
A first set of accounts can cover more or less than twelve months. Do not describe a short period as a complete year simply because it is the first set prepared. The dates determine what the figures represent.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Separate accounts from personal tax years
Business accounts and personal tax records can describe different periods. A company may have a financial year end that differs from the personal tax year.
Put the relevant dates beside each document. A tax calculation, tax year overview and set of company accounts should not be expected to contain interchangeable figures merely because they relate to the same person.
Understand why lender policies differ
Lenders set their own trading-history and evidence requirements. Halifax publishes criteria allowing consideration after at least one full year in defined circumstances, with individual assessment. Nationwide’s published self-employment evidence requirements describe two years.
These examples illustrate different approaches rather than recommend either lender. Meeting a minimum-history condition does not establish that the income, property and rest of the application will be accepted.
Identify the income relevant to your structure
For a sole trader, turnover and profit are different figures. For a partnership, your share needs to be distinguished from the business total. A company director’s salary and dividends are different from company receipts.
An adviser needs to establish the lender’s assessment method. Do not add every amount across accounts and tax records: the same income can appear in more than one place.
Keep final results separate from drafts
A draft set of accounts, management information and a forecast describe different stages of information. Label each accurately and identify who prepared it.
An accountant’s forecast may explain expected activity, but it does not turn future receipts into completed earnings. Ask which documents the potential lender requires and whether the available final records meet those requirements.
Explain earlier work in context
Previous employment or work in the same occupation may help describe your experience. Keep the dates and nature of that work clear.
Earlier salary does not automatically become current self-employed income. It can provide background without being added to the new business profit as if both were ongoing at the same time. The lender’s method governs the relevant calculation.
Describe a change in business structure
If you previously traded as a sole trader and now operate through a company, distinguish the overall trading history from the age of the company. The records should show when each arrangement applied.
A structural change may be treated differently from a completely new activity, depending on lender criteria. It does not justify combining overlapping periods or assuming every lender will regard the history as continuous.
Bring recent trading up to date
The latest accounts end at a particular date. A lender may need further evidence about the period since, such as business statements or current financial information.
Explain material changes, including reduced work, a new business activity or an important contract ending. Current receipts can help describe trading, but they do not automatically increase the annual income used for affordability.
Example: twelve months followed by further trading
Imagine a designer has final accounts for twelve months and then trades for another four months before enquiring about a mortgage. They organise the completed accounts separately from the newer statements.
The completed period establishes historical results; the later records help explain what happened afterwards. Neither should be silently annualised or merged to create a figure unsupported by the lender’s calculation.
Prepare the requested evidence
Depending on the lender and arrangement, useful records may include:
- Finalised accounts with clear period dates.
- Requested tax calculations and matching overviews.
- Business and personal statements.
- Ownership and trading-start information.
- An explanation of changes since the accounts date.
HMRC provides guidance on obtaining tax calculations and overviews. An adviser can establish which years and document formats the lender accepts.
Keep the rest of the application in view
A short trading history is only one factor. Household spending, borrowing, the deposit source, the proposed property and other relevant circumstances remain part of the assessment.
There is no universal deposit percentage that overcomes income evidence requirements. Whether applying now or later fits your situation requires personal mortgage advice, rather than a fixed waiting rule in a general guide.
Frequently asked questions
Does one set of accounts always represent a full year of trading?
No. Opening accounting periods vary. Check the actual start and end dates and when the business began trading.
Will every lender consider an application with one year of accounts?
No. Trading-history and evidence policies differ. Any lender considering the case still assesses the wider application.
Can a forecast automatically be added to completed earnings?
No. Forecasts concern expected activity. The lender decides which evidenced income it accepts and how it calculates affordability.
Important information and Mortgage Bridge’s role
Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Free, independent debt advice is available through MoneyHelper’s debt advice locator. Business Debtline explains its business-debt services and geographical coverage.
Read about us, our terms and conditions and our privacy policy.
Sources and review
- Kensington: published self-employed criteria (one lender’s policy)
- HMRC: tax calculations and overviews
- Halifax: lending criteria
- Nationwide: self-employment income
- FCA Handbook: responsible lending
Review date: 26 October 2026. Information and lender criteria may change. General information only; not a personal recommendation.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report