

Credit history changes can follow account updates, corrections, debt repayments or the end of a reporting period. These events have different meanings and do not create a standard point at which someone qualifies for a mortgage.
Mortgage availability depends on individual circumstances, supporting evidence, affordability and the lender’s current criteria. A higher credit score, corrected record or period without missed payments does not guarantee acceptance.
What credit history changes can involve
“Credit repair” is an informal phrase rather than a standard mortgage assessment category. It may refer to correcting inaccurate information, changes in account balances or payment history, or the repayment of debts.
Correcting an error is different from removing accurate information about previous payment difficulties. Repaying a debt does not necessarily remove its earlier payment history or an associated default or court judgment.
Is there a waiting period after a credit record changes?
There is no universal mortgage waiting period after a correction, repayment or credit-score change. The relevance of a change depends on the underlying information, the lender’s requirements and the rest of the application.
A credit-report update is not a mortgage eligibility milestone. Nor is there a general rule that three, six or twelve months of subsequent payment history establishes acceptance. Waiting longer does not guarantee that a mortgage will become available.
Does an improved credit score establish eligibility?
No. Credit reference agencies calculate scores using their own methods and may hold different information. Lenders may use their own scoring and assessment methods, drawing on credit-report information, the application and information they already hold.
A consumer credit score does not assess mortgage affordability or suitability. A change in that score cannot determine whether a particular lender will approve an application.
How do repayment and reporting dates differ?
The date a debt is paid is not always the date used to calculate how long a record remains visible:
- Defaults: a default normally remains on a credit report for six years from the default date, even if the debt is repaid during that period. Repayment does not restart that reporting period.
- County Court Judgments in England and Wales: a CCJ normally remains on the register and credit reports for six years from the judgment date. Full payment within one calendar month can allow removal through the court. Full payment after that period can allow it to be marked satisfied, but it normally remains for the rest of the six-year period.
- Debt management plans: completion does not establish that associated account records, defaults or other adverse entries have been removed. The individual records and their relevant dates still matter.
Removal from a credit report does not establish mortgage eligibility. Application questions may cover different periods and need to be answered accurately within their stated scope.
What if information on a credit report is wrong?
Inaccurate information can be disputed with the credit reference agency holding the report and the organisation that supplied the entry. The ICO explains the responsibilities of both organisations for credit-file accuracy.
Correction and reporting times depend on the issue and the organisations involved. There is no standard update cycle after which a mortgage lender must accept the corrected record or approve an application.
Eligibility, affordability and suitability are different
Visual explanation: eligibility, affordability and suitability
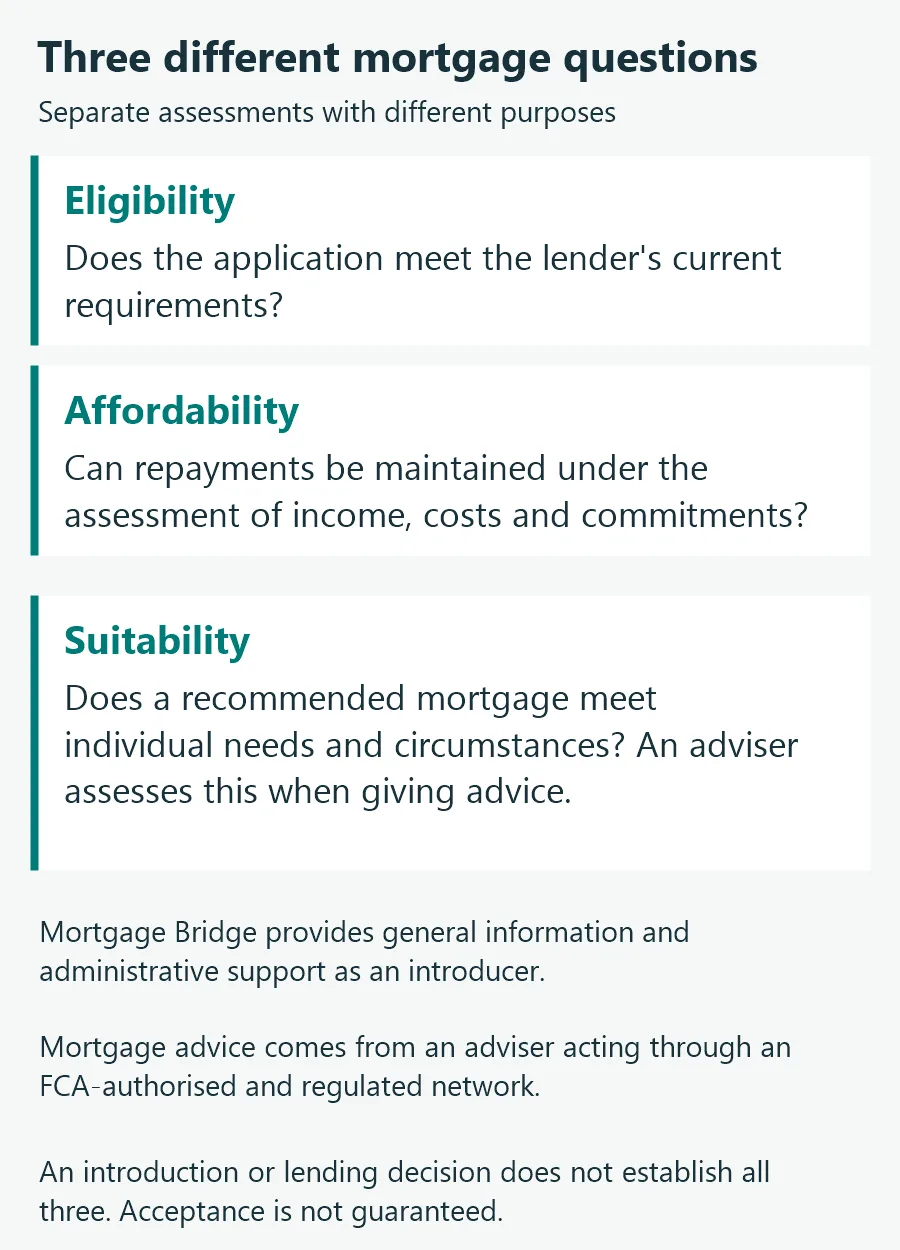
- Eligibility: whether an application meets a lender’s requirements, including its credit-history, property and borrowing criteria. Meeting initial criteria does not guarantee an offer.
- Affordability: whether repayments can be maintained. Lenders assess income and expenditure under applicable rules, including relevant commitments and foreseeable changes. Assessment methods vary.
- Suitability: whether a mortgage recommendation is appropriate for an individual’s needs and circumstances. When mortgage advice is provided, this is assessed by an adviser acting through an FCA-authorised and regulated network.
A lender may require evidence about credit history, income, expenditure, deposit funds and the property. An explanation of previous difficulties does not override its criteria, and a lender’s willingness to lend does not by itself establish suitability.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Independent debt support and secured-borrowing risks
This guide does not recommend repaying debts, changing credit use or delaying an application to improve mortgage prospects. Free, independent debt advice is available through MoneyHelper’s debt advice locator, including help understanding options where payments are difficult.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs: a longer repayment term and fees can increase the total amount repaid.
Mortgage Bridge’s role and referral payment
Mortgage Bridge provides general information and administrative support and can introduce customers to an adviser. Any information review by Mortgage Bridge is administrative only; it is not a lending decision or an assessment of mortgage eligibility, affordability or suitability.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. An introduction does not guarantee a mortgage offer or completion.
Read more about Mortgage Bridge, our terms and conditions and our privacy policy.
Frequently asked questions
How long must someone wait after a credit record changes?
There is no universal mortgage waiting period. The relevance of a change depends on the underlying information, individual circumstances, affordability and the lender’s current criteria. Elapsed time does not guarantee acceptance.
Does an improved credit score guarantee mortgage approval?
No. Lenders may use their own scoring and assessment methods alongside application information. A consumer credit score does not establish mortgage eligibility, affordability or suitability.
Does repaying a default remove it from a credit report?
No. A default normally remains on a credit report for six years from the default date, even if the debt is repaid during that period. Repayment does not restart that reporting period.
Can inaccurate credit-report information be disputed?
Yes. Inaccurate information can be disputed with the credit reference agency holding the report and the organisation that supplied the entry. Correcting an error does not guarantee mortgage acceptance.
Does Mortgage Bridge assess eligibility or recommend mortgages?
No. Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not assess eligibility or suitability or provide mortgage or debt advice. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review date
- Experian: how credit scores are calculated
- Experian: defaults and credit reports
- ICO: credit information and accuracy
- GOV.UK: CCJs and your credit rating
- Registry Trust: CCJ payment and reporting
- FCA Handbook: responsible lending
- FCA Handbook: mortgage advice and suitability
- MoneyHelper: debt consolidation risks and costs
Last reviewed: . Information and lender criteria may change. This article provides general information only and is not a personal recommendation.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report