
Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Irregular shifts can produce different patterns of work and pay. A recent rota or payment does not guarantee a continuing annual level of income.
Variable earnings need to be distinguished from contractual basic pay. A bonus, commission payment or a high month of overtime can describe past receipts without establishing the figure a lender will use.
This guide explains the history, conditions and continuity behind earnings. It gives no universal inclusion percentage or evidence period and does not recommend taking extra shifts or changing pay arrangements to qualify for borrowing.
Irregular shifts: How variable earnings may be interpreted
Overtime, bonuses, commission and fluctuating hours can produce earnings above basic pay. Their frequency, history, contractual basis and expected continuation may affect the amount a lender recognises. Different sources can receive different treatment within the same application. A payment described as a bonus is not necessarily guaranteed, and the latest high month may not represent ongoing earnings.
A lender may average records over its chosen period, apply a proportion or exclude a source. Its requirements can also differ when employment has changed or income has recently fallen. No universal percentage or evidence period is used here. A historical total is useful evidence of past receipts, but it cannot guarantee future payments or establish mortgage affordability by itself.
Allowances, earnings and reimbursed expenses
An allowance label can cover different arrangements. A payment for contractual duties, a variable shift premium and reimbursement of a work expense do not establish the same amount of available personal income. The payslip description, employment terms and payment history help explain what the money represents. A lender can ask whether it continues after a change in hours, location or housing.
An annual total alone cannot resolve those distinctions. The same employee may receive several payments with different conditions, and one lender’s treatment does not bind another. Records may need to distinguish normal earnings from back pay or an exceptional adjustment. This guide does not treat every allowance as mortgage income or recommend changing working patterns to increase borrowing.
Several jobs and overlapping income records
When someone has more than one employer, the income from each role needs a separate explanation. Different start dates, contracts and pay cycles can make one combined total misleading. A bank shift might already be included in a main employer’s payslip, while an agency payment might have a separate payroll record. The same earnings must not be counted twice.
A lender’s assessment may consider the history and continuation of each source rather than simply adding the latest payments. Changes in hours or the loss of one role can also affect the picture. Payslips, employment details and relevant tax records can help reconcile the sources. This guide does not recommend taking a second job or more shifts as a way to obtain a mortgage.
What income evidence can establish
Payslips, employment records, tax documents or business accounts can explain where earnings come from and how they are paid. The appropriate evidence depends on the source and the lender. Some information can be verified electronically; other applications require documents or clarification. There is no single document list or number of payslips that applies to every borrower.
Evidence of money received is not automatically evidence that it is recurring personal income. An account credit could be a transfer, reimbursement, loan or business receipt. A lender may need to distinguish these from earnings available for mortgage payments. A clear explanation can resolve a question about a record, but it does not oblige the lender to accept the income.
Contracts, job changes and actual earnings
Permanent, fixed-term, temporary, agency and zero-hours work can produce different evidence. The legal employer may differ from the place where a person works, and a headline contract rate may differ from personal pay. Contract duration, work history, gaps and evidence of continuation can matter under the lender’s policy.
No universal number of months in a job establishes acceptance. A professional title, expected promotion or future salary is not automatically treated as current income. Some applications require an employer’s explanation or additional records; others use electronic verification. This guide does not recommend changing employment or selecting a contract arrangement to qualify. The actual circumstances and permitted income method determine what is assessed.
How affordability differs from a headline income figure
Income establishes only part of a mortgage assessment. The lender also considers expenditure, existing financial commitments and relevant foreseeable changes under the rules that apply to the loan. Gross salary, take-home pay and the income a lender recognises are different figures. An online borrowing estimate cannot establish which amount will be accepted.
An income multiple can be a limit within a lender’s policy without being the amount it will offer. Property value, credit requirements and the requested term can impose separate restrictions. Two applicants earning the same amount can receive different decisions because their costs and circumstances differ. This guide does not set a universal salary threshold or promise a particular advance.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Existing commitments and household costs
Loan payments, credit cards, hire purchase, childcare, maintenance and other regular expenses can affect an affordability assessment. Housing, travel and costs for dependants may also be relevant. The lender decides how commitments are entered and assessed; it is unsafe to assume that every payment is treated identically or ignored below a particular amount.
The balance owed and the monthly payment describe different aspects of a debt. A commitment ending soon may require evidence, while a future obligation can still matter. Paying off debt, using savings or changing repayment arrangements can have wider consequences. This article does not recommend those steps to obtain a mortgage; it explains why an accurate picture of continuing costs is part of assessment.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
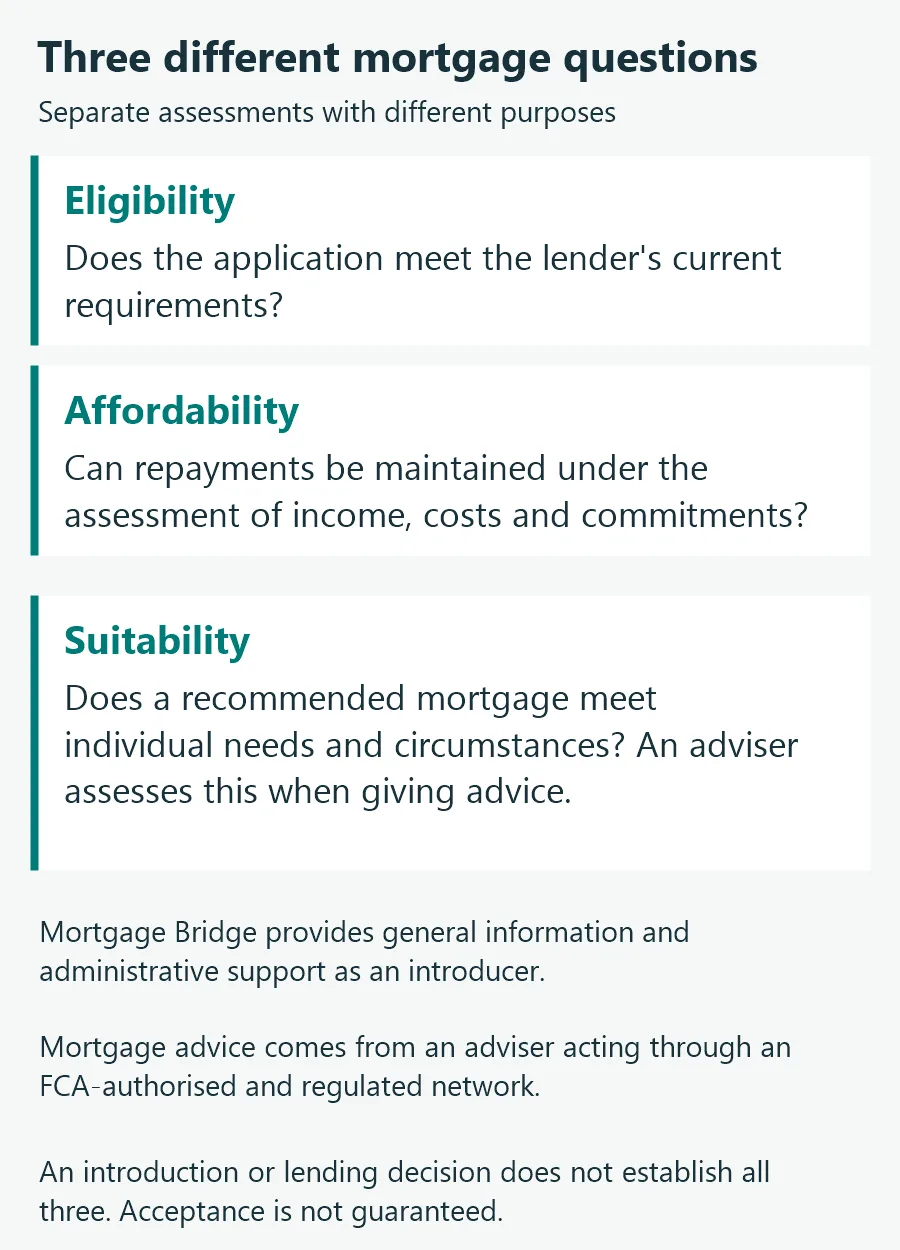
Eligibility means meeting a lender’s current requirements. Affordability concerns maintaining payments under the relevant assessment of income, costs and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances; an adviser assesses this when giving advice. An initial check, valuation or lender approval does not establish all three.
The outcome depends on individual circumstances, supporting evidence, affordability, the property and lender criteria. Acceptance is not guaranteed.
Debt support and Mortgage Bridge’s role
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, taking new credit or using savings to obtain a mortgage.
Any review by Mortgage Bridge is administrative only. An introduction is not a lending decision or a personal recommendation. Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Read about us, our terms and conditions and our privacy policy.
Frequently asked questions
Does receiving variable pay mean it will count in full?
No. The lender’s policy and the payment history, conditions and expected continuation determine how it may be assessed.
Can the latest high payment be treated as annual income?
Not automatically. Exceptional payments and fluctuations may require comparison with other records and clarification of the underlying arrangement.
Does meeting eligibility criteria establish affordability or suitability?
No. Eligibility concerns lender requirements; affordability concerns the ability to maintain payments; suitability concerns the individual needs assessed when an adviser makes a recommendation. These are separate questions.
Does Mortgage Bridge give personal mortgage or debt advice?
No. Mortgage Bridge provides general information and administrative support as an introducer. It does not assess eligibility, affordability or suitability or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review
- Nationwide: employment income criteria (one lender’s policy)
- FCA: responsible lending and affordability
- Nationwide: outgoing commitments (one lender’s policy)
- MoneyHelper: applying for a mortgage
- Nationwide: self-employed income evidence (one lender’s policy)
- Halifax: mortgage criteria (one lender’s policy)
- Nationwide: affordability criteria (one lender’s policy)
- FCA: advised mortgage sales and suitability
- MoneyHelper: secured debt and consolidation costs
Lender pages illustrate individual policies, not universal requirements or recommendations.
Last reviewed: . This article is subject to periodic review. Information, rules and lender criteria may change.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report