

Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Buying a rented home at a discount still involves a new purchase and mortgage assessment. A private discounted sale differs from a statutory purchase scheme.
This guide focuses on the sale agreement, rent history and how the lender treats the proposed discount. A tenancy is not proof of ownership or accepted mortgage security. It does not promise no-deposit borrowing or advise ending the tenancy before the legal position is established.
Buying a rented home at a discount: What a concessionary purchase involves
A concessionary purchase is a sale at a genuine discount to the value accepted for the transaction. In permitted circumstances a lender may recognise the difference as gifted equity, but not every discounted property or relationship meets its policy. A low asking price is not automatically a gift of equity.
The sale contract, valuation and mortgage application need to describe the arrangement consistently. Repayment conditions, retained interests or a seller remaining in occupation may change the assessment. Family sales, landlord-to-tenant sales and formal housing schemes can have different requirements. This article does not present a discount as guaranteed deposit funding or assume the lender’s valuation will match the parties’ estimate.
Gifted equity is not a cash transfer
Gifted equity can describe value transferred through a discounted sale rather than money paid into the buyer’s account. A cash gifted deposit is different: funds move from a donor towards a purchase. The lender determines whether either arrangement is permitted and how the purchase price and accepted value enter its calculation.
A discount is not cash available for legal fees, taxes or repairs. A lender may still require a buyer’s contribution and evidence of other purchase funds. The parties cannot assume that writing a higher value into documents creates usable equity. Ownership, repayment and occupation conditions must reflect the real agreement. Mortgage acceptance also does not settle the seller’s tax position or the buyer’s legal interests.
Legal checks on a discounted or connected-party sale
The conveyancer may need to establish the parties, relationship, sale terms, title and any retained rights. Existing mortgages or charges must also be dealt with through the legal process. A transaction between relatives or a landlord and tenant is not exempt from identity and source-of-funds requirements merely because the parties know each other.
The lender’s instructions can require particular confirmations about the discount or occupation. Separate legal advice may be relevant where interests differ; this article cannot decide that for the parties. Questions about insolvency, undue influence, beneficial interests or repayment conditions require legal assessment rather than a mortgage workaround. A completed checklist does not guarantee that the transaction will satisfy the lender or conveyancer.
A lender’s valuation is different from a buyer’s survey
A mortgage valuation addresses the property as security for the lender. It can use different methods and may not involve the level of inspection a buyer expects from a survey. A valuation does not certify that the building is free of defects, establish all repair costs or replace the conveyancer’s title checks.
The accepted value can differ from the agreed price or an estate agent’s estimate. Conditions, additional reports or legal information may affect the lender’s position. Paying for a valuation does not guarantee an offer. A buyer’s survey has its own scope, limitations and purpose; the appropriate service is a matter for the relevant professional rather than a mortgage approval outcome.
How affordability differs from a headline income figure
Income establishes only part of a mortgage assessment. The lender also considers expenditure, existing financial commitments and relevant foreseeable changes under the rules that apply to the loan. Gross salary, take-home pay and the income a lender recognises are different figures. An online borrowing estimate cannot establish which amount will be accepted.
An income multiple can be a limit within a lender’s policy without being the amount it will offer. Property value, credit requirements and the requested term can impose separate restrictions. Two applicants earning the same amount can receive different decisions because their costs and circumstances differ. This guide does not set a universal salary threshold or promise a particular advance.
Documents serve different verification purposes
Identity and address evidence identifies the applicant; income and account records help explain finances; deposit documents address purchase funds. Property and legal papers concern the security and transaction. A record supplied for one purpose may not answer a different question. The lender and conveyancer can request different information even in the same purchase.
The relevant document period and format depend on the case. A generic checklist cannot guarantee completeness, and electronic verification may affect what is requested. Missing, inconsistent or outdated information can lead to questions, but providing a complete set does not establish acceptance. The lender still applies its criteria, while the conveyancer carries out the legal work within the terms of the instruction.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
The purchase and mortgage processes are separate
A buyer can have a price accepted while valuation, underwriting, searches and legal enquiries are still outstanding. Mortgage approval concerns the loan; the purchase contract and transfer of title are separate. Delays can arise from chains, documents, property issues or unresolved conditions, so there is no guaranteed completion timetable.
In England and Wales, an accepted offer is generally not legally binding until contracts are exchanged. Scotland and Northern Ireland have different processes, and local legal advice matters. Completion brings further steps such as funds transfer and registration through the conveyancer. A general description of stages cannot confirm that a particular buyer is ready to make a binding commitment.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
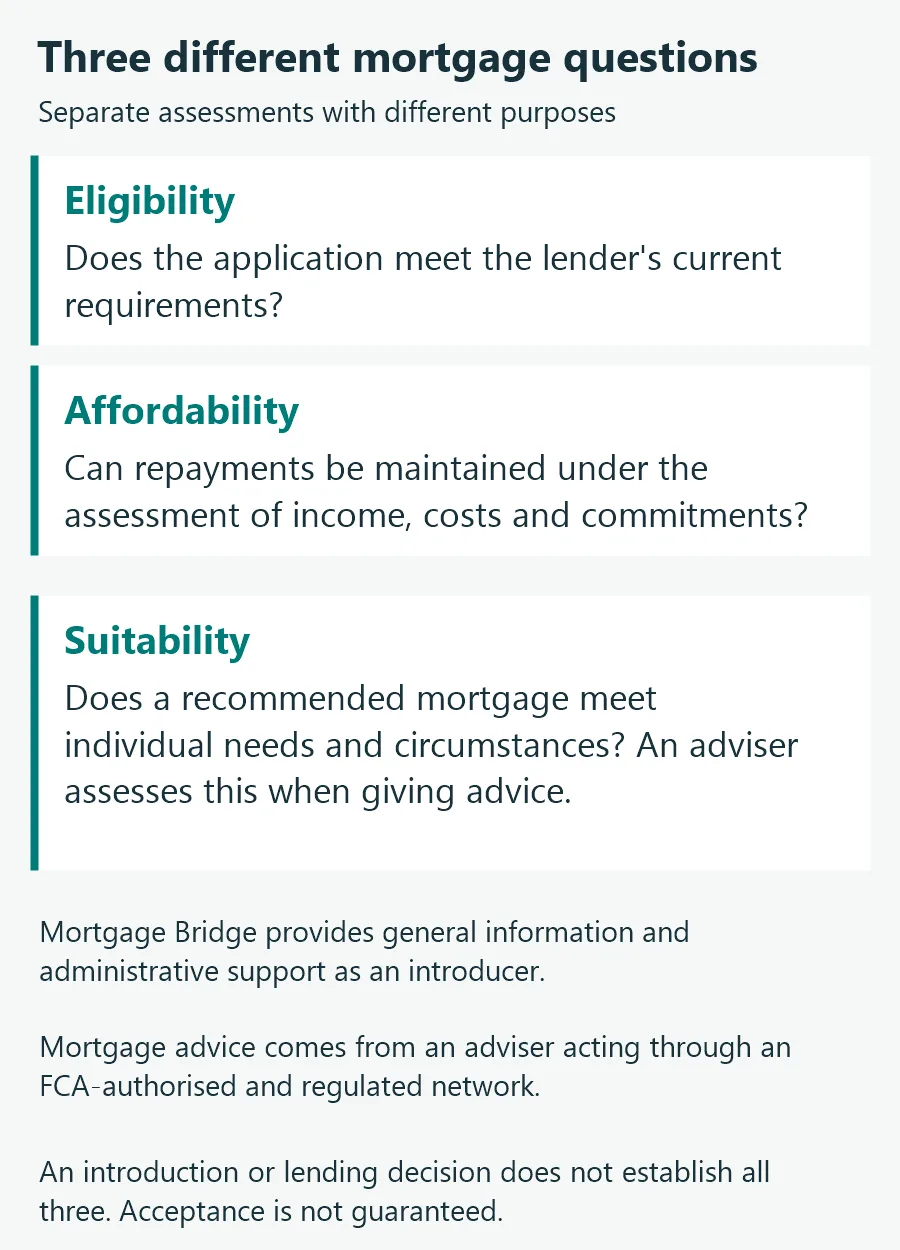
Eligibility means meeting a lender’s current requirements. Affordability concerns maintaining payments under the relevant assessment of income, costs and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances; an adviser assesses this when giving advice. An initial check, valuation or lender approval does not establish all three.
The outcome depends on individual circumstances, supporting evidence, affordability, the property and lender criteria. Acceptance is not guaranteed.
Debt support and Mortgage Bridge’s role
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, taking new credit or using savings to obtain a mortgage.
Any review by Mortgage Bridge is administrative only. An introduction is not a lending decision or a personal recommendation. Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Read about us, our terms and conditions and our privacy policy.
Frequently asked questions
Is a private landlord discount the same as Right to Buy?
No. A private concessionary sale and statutory housing schemes have different rules.
Does living in the property guarantee it is acceptable security?
No. Valuation, title and lender property requirements still need assessment.
Does meeting eligibility criteria establish affordability or suitability?
No. Eligibility concerns lender requirements; affordability concerns the ability to maintain payments; suitability concerns the individual needs assessed when an adviser makes a recommendation. These are separate questions.
Does Mortgage Bridge give personal mortgage or debt advice?
No. Mortgage Bridge provides general information and administrative support as an introducer. It does not assess eligibility, affordability or suitability or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review
- Nationwide: concessionary purchase criteria (one lender’s policy)
- Halifax: mortgage, deposit, conviction and property criteria (one lender’s policy)
- SRA: identity and source-of-funds checks
- HMRC: SDLT and property transfers
- MoneyHelper: buying and mortgage costs
- GOV.UK: buying a home in England and Wales
- Nationwide: valuation policy (one lender’s requirements)
- FCA: responsible lending and affordability
- Nationwide: affordability criteria (one lender’s policy)
- MoneyHelper: applying for a mortgage
- FCA: advised mortgage sales and suitability
- MoneyHelper: secured debt and consolidation costs
Lender pages illustrate individual policies, not universal requirements or recommendations.
Last reviewed: . This article is subject to periodic review. Information, rules and lender criteria may change.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report