
Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
First-time buyer credit issues need to be considered separately from a lender’s definition of a first-time buyer. Meeting a product definition does not settle the treatment of defaults, arrears or insolvency, or establish mortgage acceptance.
This guide explains the evidence and purchase stages relevant to that distinction. It does not treat an explanation, settlement or the passage of time as a route to approval. The property, current financial commitments and intended borrowing remain part of the decision.
First-time buyer credit issues and lender requirements
Missed payments, defaults, court judgments, debt arrangements and insolvency are different events. A lender may consider their dates, amounts, current status and surrounding circumstances under its criteria. Settlement or elapsed time does not automatically make an event irrelevant. There is no standard waiting period after which a mortgage must be available.
A larger deposit or an explanation does not require a lender to set aside a credit restriction. An explanation may provide context, but acceptance still depends on the full assessment. This guide does not promise a specialist lender or describe another borrower’s success as evidence of an available outcome. Where debt payments are difficult, independent debt advice addresses a different need from a mortgage enquiry.
Credit reports, scores and lender decisions
A consumer credit score is a summary produced using a provider’s method. The lender can use its own assessment and other information, so there is no single score that guarantees a mortgage. Account history, public records and identity or address information may be relevant alongside the income, property and borrowing requested.
Credit information can differ between agencies or take time to update. The ICO explains rights of access and how inaccurate information can be challenged. Correcting an error is different from removing accurate history, and neither establishes a lending outcome. A high score does not demonstrate affordability, while a limited file is not the same thing as a history of missed payments.
How affordability differs from a headline income figure
Income establishes only part of a mortgage assessment. The lender also considers expenditure, existing financial commitments and relevant foreseeable changes under the rules that apply to the loan. Gross salary, take-home pay and the income a lender recognises are different figures. An online borrowing estimate cannot establish which amount will be accepted.
An income multiple can be a limit within a lender’s policy without being the amount it will offer. Property value, credit requirements and the requested term can impose separate restrictions. Two applicants earning the same amount can receive different decisions because their costs and circumstances differ. This guide does not set a universal salary threshold or promise a particular advance.
Deposit, price and loan-to-value
The purchase deposit is the part of the price not met by the mortgage advance. Loan-to-value compares borrowing with the value used by the lender, which may not equal the agreed price. Deposit size and the source of that deposit are separate questions. Neither a percentage nor a large cash balance establishes all lending requirements.
A lower valuation can increase the funding gap without changing what the seller wants to receive. Affordability can also restrict borrowing below a product’s maximum loan-to-value. Fees and purchase expenses may need additional funds. This guide therefore does not present a universal deposit range or suggest that a larger contribution automatically overrides income, credit, property or legal restrictions.
Documents serve different verification purposes
Identity and address evidence identifies the applicant; income and account records help explain finances; deposit documents address purchase funds. Property and legal papers concern the security and transaction. A record supplied for one purpose may not answer a different question. The lender and conveyancer can request different information even in the same purchase.
The relevant document period and format depend on the case. A generic checklist cannot guarantee completeness, and electronic verification may affect what is requested. Missing, inconsistent or outdated information can lead to questions, but providing a complete set does not establish acceptance. The lender still applies its criteria, while the conveyancer carries out the legal work within the terms of the instruction.
An agreement in principle is an initial indication
An agreement or decision in principle is based on a lender’s preliminary assessment. It is not a mortgage offer, a final valuation or a promise that the purchase will complete. The information considered and checks made differ between lenders, and further evidence can change the result when a full application is assessed.
The indicated amount may depend on assumptions about income, commitments, deposit and the proposed transaction. A seller’s acceptance of an offer does not confirm those assumptions. Any validity period or conditions come from the particular lender, not a universal timetable. An agreement in principle also does not establish that a recommended mortgage would meet the buyer’s individual needs or that the property is acceptable security.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
The deposit is only one part of buying costs
Purchase costs can include legal work, searches, surveys, valuation charges, mortgage fees, registration and any relevant property tax. Some costs arise before completion and may not be refundable if the purchase stops. The amount and timing depend on the transaction and the services used, rather than one standard allowance.
After completion there can be household bills, insurance, repairs and, for some properties, service charges or ground rent. A lender’s assessment and a buyer’s full ownership costs are related but not identical. A headline monthly mortgage payment does not show every outgoing. This article does not prescribe a savings target or recommend using money reserved for other commitments to meet a deposit.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
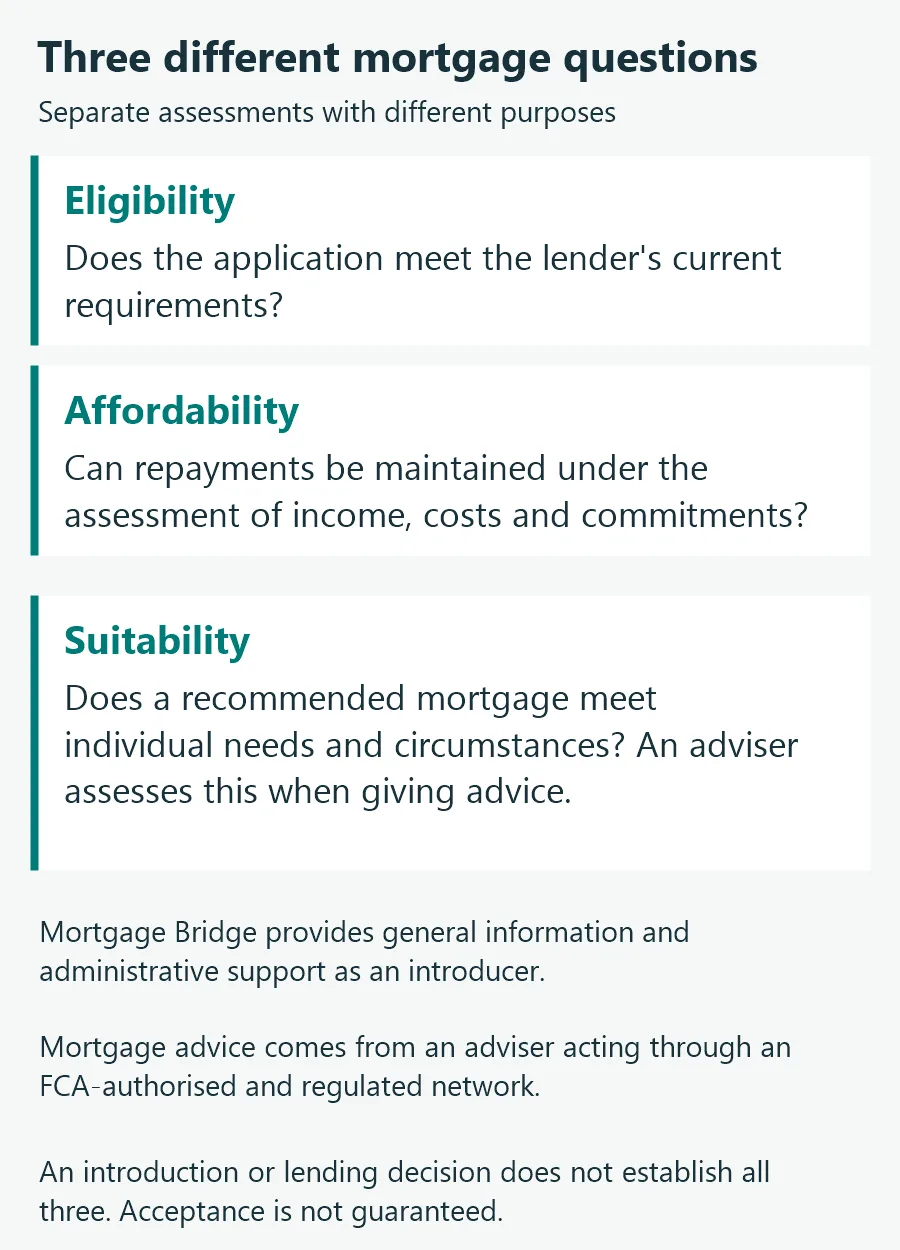
Eligibility means meeting a lender’s current requirements. Affordability concerns maintaining payments under the relevant assessment of income, costs and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances; an adviser assesses this when giving advice. An initial check, valuation or lender approval does not establish all three.
The outcome depends on individual circumstances, supporting evidence, affordability, the property and lender criteria. Acceptance is not guaranteed.
Debt support and Mortgage Bridge’s role
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, taking new credit or using savings to obtain a mortgage.
Any review by Mortgage Bridge is administrative only. An introduction is not a lending decision or a personal recommendation. Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Read about us, our terms and conditions and our privacy policy.
Frequently asked questions
Does first-time buyer status relax credit requirements?
Not automatically. A lender’s first-time buyer product definition and credit requirements are separate. The full application must meet its current criteria.
Does settling a previous debt establish acceptance?
No. Settlement can update the evidence, but credit policy, affordability, property requirements and other circumstances still affect the outcome.
Does meeting eligibility criteria establish affordability or suitability?
No. Eligibility concerns lender requirements; affordability concerns the ability to maintain payments; suitability concerns the individual needs assessed when an adviser makes a recommendation. These are separate questions.
Does Mortgage Bridge give personal mortgage or debt advice?
No. Mortgage Bridge provides general information and administrative support as an introducer. It does not assess eligibility, affordability or suitability or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review
- ICO: credit records, checks and inaccurate information
- Halifax: mortgage, deposit, conviction and property criteria (one lender’s policy)
- MoneyHelper: secured debt and consolidation costs
- FCA: responsible lending and affordability
- Nationwide: affordability criteria (one lender’s policy)
- MoneyHelper: applying for a mortgage
- SRA: identity and source-of-funds checks
- MoneyHelper: buying and mortgage costs
- GOV.UK: buying a home in England and Wales
- GOV.UK: current and future leasehold reforms
- FCA: advised mortgage sales and suitability
Lender pages illustrate individual policies, not universal requirements or recommendations.
Last reviewed: . This article is subject to periodic review. Information, rules and lender criteria may change.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report