

Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Mortgage application documents can identify the applicant, explain finances or concern the property. A general checklist does not establish exactly what a particular lender will require.
A mortgage assessment draws on several kinds of information, including the borrower’s finances and the property. A request for clarification, a referral to a person and an automated result do not necessarily mean the same thing.
This guide explains verifiable parts of the process. It does not infer how an individual underwriter feels, claim discretion overrides policy or promise that presenting information in a particular way will produce approval.
Mortgage documents: match the record to the question
A useful document pack explains identity, income, commitments, purchase funds and the property. One record can contribute to several checks without settling them all. The table below is an organising aid, not a universal list of compulsory documents or a guarantee that alternatives will be accepted.
| Question | Examples of relevant records | Who may request them | Important limit |
|---|---|---|---|
| Who is applying? | Identity and address documents or an accepted electronic verification route. | The lender, adviser or conveyancer for their respective checks. | Acceptable records and dates must be confirmed with the recipient. |
| Where does employed income come from? | Payslips, employment information and corresponding receipts. | The lender or adviser preparing the application. | Net pay, gross pay and accepted mortgage income are not interchangeable. |
| What supports self-employed income? | Requested accounts, tax calculations, overviews and current trading records. | The lender or adviser; an accountant may explain the records. | Match the periods and business structure; do not add overlapping figures. |
| What commitments continue? | Credit agreements, balances, statements and relevant household-cost information. | The lender or adviser. | A monthly payment is different from the balance owed or a credit limit. |
| Where is the purchase money from? | Savings histories, gift terms, sale or distribution records and transfer links. | The lender and conveyancer for different responsibilities. | A balance alone does not establish origin or ownership. |
| What property and legal issues remain? | The documents requested for valuation, title, lease or building matters. | The lender, valuer or conveyancer within their instructions. | An accepted income document does not resolve a property or legal condition. |
A fictional pack: connect the same payment across records
A buyer’s payslip shows £3,000 gross pay, £650 deductions and £2,350 net pay. Their bank statement shows a £2,350 receipt. Those are connected records of the same pay, not separate income amounts to add together. A £600 transfer from the buyer’s savings account is a different movement and should be explained separately.
For a self-employed buyer, business receipts, expenses, profit and personal transfers require a different interpretation. Our one-year-accounts guide includes a document-period example.
Check scope, dates and format before submitting
- Confirm which applicant, account and period the request covers.
- Use the genuine complete record in the format requested, including all relevant pages.
- Keep the source document separate from your explanatory note.
- Ask whether electronic verification or an alternative record is accepted; do not assume it is.
- Explain missing information and material changes rather than silently substituting a different period.
- Send through the agreed secure channel and ask what is required before sharing unrelated sensitive information.
MoneyHelper’s mortgage application guide provides a general preparation checklist. The lender’s actual request and the conveyancer’s separate instructions still matter. Providing every requested document does not, by itself, establish affordability or suitability.
Keep specialist evidence questions separate
See our bank-statement examples, purchase-fund record chains and gifted-deposit checklist. These resources explain what different records can show; none is an approval checklist.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
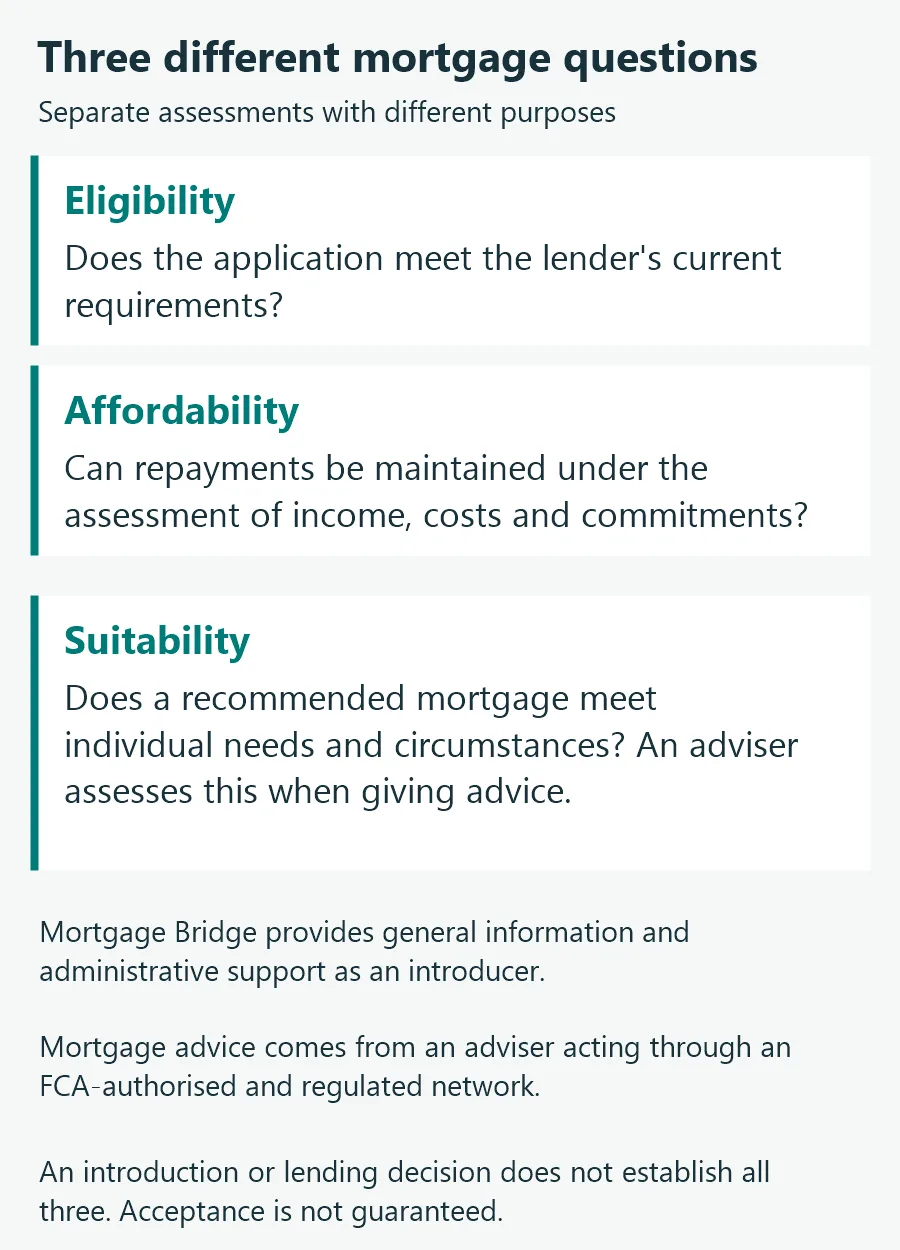
Eligibility means meeting a lender’s current requirements. Affordability concerns maintaining payments under the relevant assessment of income, costs and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances; an adviser assesses this when giving advice. An initial check, valuation or lender approval does not establish all three.
The outcome depends on individual circumstances, supporting evidence, affordability, the property and lender criteria. Acceptance is not guaranteed.
Debt support and Mortgage Bridge’s role
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, taking new credit or using savings to obtain a mortgage.
Any review by Mortgage Bridge is administrative only. An introduction is not a lending decision or a personal recommendation. Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Read about us, our terms and conditions and our privacy policy.
Frequently asked questions
Does a human review mean the lender can ignore its criteria?
No. The applicable policy and rules remain relevant. A review can clarify facts or apply the lender’s process without requiring acceptance.
Does a request for further information mean a decline?
Not necessarily. The actual request and stage need to be established; a question or referral is different from a final lending decision.
Does meeting eligibility criteria establish affordability or suitability?
No. Eligibility concerns lender requirements; affordability concerns the ability to maintain payments; suitability concerns the individual needs assessed when an adviser makes a recommendation. These are separate questions.
Does Mortgage Bridge give personal mortgage or debt advice?
No. Mortgage Bridge provides general information and administrative support as an introducer. It does not assess eligibility, affordability or suitability or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review
- FCA: responsible lending and affordability
- MoneyHelper: applying for a mortgage
- Halifax: mortgage criteria (one lender’s policy)
- SRA: identity and source-of-funds checks
- Nationwide: employment income criteria (one lender’s policy)
- Nationwide: self-employed income evidence (one lender’s policy)
- Nationwide: affordability criteria (one lender’s policy)
- ICO: credit records, checks and inaccurate information
- MoneyHelper: buying and mortgage costs
- GOV.UK: buying a home in England and Wales
- Nationwide: valuation policy (one lender’s requirements)
- FCA: advised mortgage sales and suitability
- MoneyHelper: secured debt and consolidation costs
Lender pages illustrate individual policies, not universal requirements or recommendations.
Last reviewed: . This article is subject to periodic review. Information, rules and lender criteria may change.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report