

Important information: Mortgage Bridge acts as a mortgage introducer and provides general information and administrative support. This guide does not constitute regulated mortgage advice, legal advice or a recommendation about using compensation. Any regulated mortgage advice is provided separately by an adviser acting through a network authorised and regulated by the Financial Conduct Authority (FCA), following an assessment of your individual circumstances.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Compensation payouts proposed as mortgage deposits require individual assessment. Someone receiving compensation or an insurance settlement may consider using some of the money towards a property purchase. Whether a lender will accept those funds as a deposit depends on its criteria, the nature of the payment, supporting evidence and the applicant’s circumstances.
Previous missed payments, defaults, County Court Judgments or other credit issues remain separate considerations. A compensation payment does not remove their effect or establish mortgage eligibility.
The outcome of any application will depend on individual circumstances, affordability, supporting evidence, property requirements and the specific criteria of the lender approached. Acceptance is not guaranteed.
Compensation payouts: can compensation be considered as a mortgage deposit?
A lender may consider funds received through compensation or an insurance settlement, subject to its requirements. There is no single acceptance rule covering every payment or applicant.
The description “compensation payout” can cover different circumstances. A payment relating to personal injury, lost earnings, property damage or another claim may involve different documents, conditions and financial considerations.
The availability of the money, its source and whether it can be used for the proposed transaction may need to be established.
Clear evidence does not require a lender to accept a deposit or approve a mortgage. Acceptance of the deposit source is only one part of the application.
Source-of-funds checks
A lender or the solicitor or conveyancer handling a purchase may need evidence of where the deposit came from.
Depending on the circumstances, documents requested may include:
-
Confirmation of the award or settlement.
-
Relevant correspondence from the solicitor, insurer or organisation making the payment.
-
Bank statements showing receipt of the money.
-
Evidence of transfers between accounts.
-
Information about ownership or restrictions affecting the funds.
This is an illustrative list, not a standard requirement applying to every firm.
A bank statement showing an available balance does not necessarily establish the underlying source of the money. The receiving firm should explain the evidence it needs and how to provide it securely.
Lenders and legal professionals carry out their own checks. A lender accepting the source of a deposit does not replace the solicitor’s checks or establish that the transaction can complete.
The Solicitors Regulation Authority provides further information about anti-money laundering checks during legal transactions.
Ownership, restrictions and the purpose of the payment
Receiving a payment does not, by itself, establish that all of it is available for a property deposit.
Relevant questions may include:
-
Who owns or controls the money.
-
Whether it is held in a trust or subject to a court order.
-
Whether consent or approval is needed before it can be used.
-
Whether the settlement includes money intended to meet future costs.
-
Whether using it could affect other financial arrangements or entitlements.
These are matters for the appropriate legal, financial or benefits professional. A mortgage adviser’s assessment does not replace advice about a trust, court order, compensation settlement or benefits entitlement.
Mortgage Bridge does not interpret settlement terms or advise whether compensation should be spent on a property.
How credit issues may affect the application
Some lenders may consider applications involving adverse credit, subject to their current criteria and an assessment of the applicant’s circumstances. Other lenders may decline particular credit histories.
Relevant factors may include:
-
The type, age, amount and number of credit issues.
-
Whether judgments or defaults remain outstanding.
-
Recent payment history.
-
Existing borrowing and commitments.
-
Income and expenditure.
-
Deposit or equity.
-
The property and proposed mortgage.
These factors are not an eligibility checklist. A period of improved payment history or an explanation of past difficulties does not guarantee acceptance.
An adviser acting through an FCA-authorised and regulated network can assess your circumstances and explain which options, if any, may be available. The lender makes the final lending decision.
Does a larger compensation-funded deposit overcome bad credit?
No. A larger deposit reduces the proportion of the property’s value being borrowed, but it does not override credit criteria, affordability requirements or source-of-funds checks.
There is no standard deposit percentage for an applicant with compensation funds and adverse credit. Requirements depend on the lender, product, property and individual circumstances.
The size of a payment does not establish which interest rate, mortgage amount or terms a lender might offer.
Compensation and mortgage affordability
A deposit and the ability to make mortgage repayments are separate parts of an assessment.
A lump sum intended for the deposit does not automatically establish an ongoing income that a lender will accept. The treatment of any recurring compensation or insurance payments depends on the lender’s criteria, the payment arrangement and supporting evidence.
A lender may also assess expenditure, existing commitments, dependants and potential changes to payments or income. Methods and assumptions vary.
This guide does not establish borrowing capacity or recommend using compensation instead of retaining it for another purpose.
Financial considerations before using compensation
Compensation may have a role in meeting future living costs, replacing earnings or supporting other needs. Using money for a deposit can reduce the amount available for those purposes.
Once used to buy a property, money is held as property equity rather than readily available cash. Accessing it later may involve a sale, further borrowing or another transaction, none of which is guaranteed.
These considerations do not establish whether buying a property is appropriate for a particular person. Individual advice may be needed about the settlement, future financial needs and any legal or benefits implications.
This guide does not recommend using compensation, repaying debts, changing payment arrangements or taking on borrowing.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
An illustrative scenario
Consider an applicant who has received an insurance settlement and also has previous missed payments recorded on their credit history.
The applicant wishes to understand whether the funds could form part of a deposit. An adviser, lender or solicitor may request relevant evidence of the settlement, receipt of funds and any restrictions on their use.
The lender would separately assess the credit history, accepted income, expenditure, property and proposed borrowing under its own criteria.
The information in this example is not enough to predict deposit acceptance, mortgage availability, interest rates or a completion outcome.
This is an illustrative scenario only. It is not a customer testimonial, an approved mortgage case or evidence that another person with similar circumstances will receive the same result.
Buy-to-let enquiries
Buy-to-let applications involve their own lending and property requirements.
A lender may consider rental income, personal financial circumstances, existing borrowing, deposit or equity and property characteristics. The treatment of compensation funds and adverse credit depends on the lender and the application.
Projected rent does not remove source-of-funds checks or establish acceptance. This guide does not recommend property investment or confirm that a buy-to-let mortgage is suitable or available.
Providing documents and sensitive information
The adviser firm operating within an FCA-authorised and regulated network, lender or solicitor should explain which documents are relevant and how to submit them securely.
Compensation documents can contain medical information or other sensitive details. Mortgage Bridge does not request detailed medical records through its initial enquiry service.
Please do not upload medical reports or detailed personal-injury evidence to Mortgage Bridge. Where a receiving professional needs such information, use the secure process that firm specifies.
Providing documents does not guarantee acceptance or remove the need for separate assessments.
How Mortgage Bridge can help
Mortgage Bridge provides general mortgage information, administrative enquiry support and adviser introductions where appropriate.
We do not assess mortgage suitability, determine eligibility, recommend products, provide regulated mortgage advice or make lending decisions. We also do not advise on the legal or financial use of compensation.
Any regulated mortgage advice is provided separately by an adviser acting through an FCA-authorised and regulated network, following an assessment of your circumstances. An introduction does not guarantee that a firm will accept or progress an enquiry.
Mortgage Bridge has commercial referral arrangements and receives a percentage of the adviser’s commission when an introduced case completes.
See About Us, our Terms and Conditions and Privacy Policy for introduction, payment and information-sharing arrangements.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
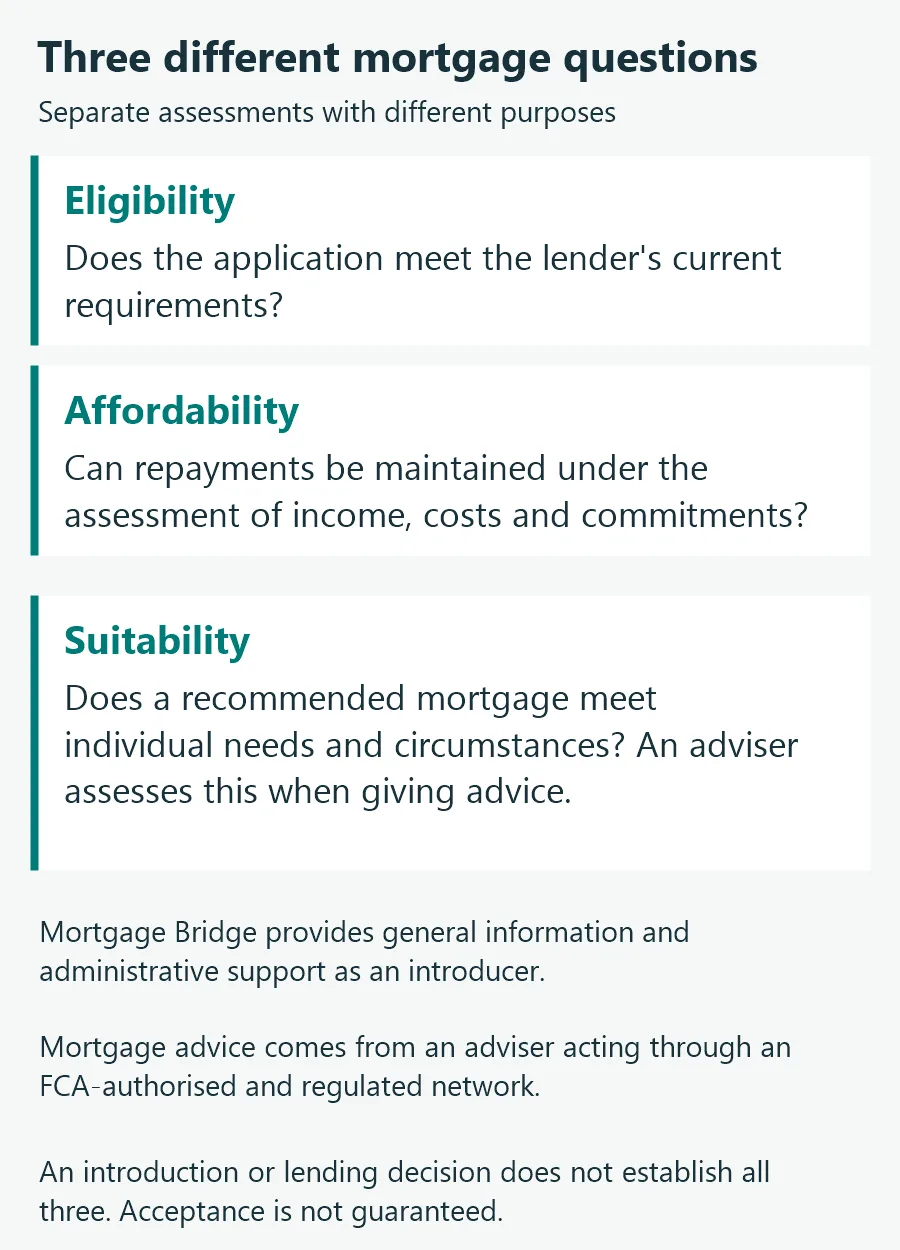
Eligibility concerns the lender’s current requirements. Affordability concerns whether repayments can be maintained, taking account of relevant income, expenditure and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances and is assessed when an adviser acting through an FCA-authorised and regulated network provides mortgage advice. Passing one assessment does not establish the others. Mortgage Bridge does not carry out these assessments or provide mortgage or debt advice.
Free independent debt support
Free, independent debt advice is available through MoneyHelper’s debt advice locator.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Frequently asked questions
Can personal injury compensation be considered as a deposit?
A lender may consider it, subject to its criteria, evidence and the applicant’s circumstances. Whether the money can lawfully and appropriately be used may require separate legal or financial advice, particularly where a trust or restriction is involved.
Does an insurance settlement count in the same way as savings?
No uniform treatment should be assumed. The lender and legal professional may require evidence of the payment and its underlying source. Requirements depend on the circumstances.
Will credit issues prevent an application from being considered?
Some lenders may consider applications involving credit issues, while others apply restrictions. The deposit source does not establish eligibility or guarantee acceptance.
Does a larger deposit guarantee better terms?
No. Deposit size is only one consideration. Credit history, affordability, property requirements, product availability and lender criteria remain relevant.
Can the payout be counted as income?
A lump sum used for a deposit does not automatically count as ongoing mortgage income. Any recurring payment requires assessment under the lender’s criteria and the relevant payment arrangement.
Can compensation held in a trust be used?
That depends on the trust terms, relevant permissions and transaction requirements. This guide cannot determine whether a withdrawal or purchase is permitted. Advice from the appropriate legal professional is needed.
Can compensation be considered for a buy-to-let deposit?
That depends on the lender, the funds and the proposed transaction. Buy-to-let criteria and source-of-funds checks apply separately. Availability is not guaranteed.
Mortgage Bridge is a mortgage introducer and does not provide regulated mortgage advice or legal advice.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Information about lender practices may change. Requirements should be checked at the time of an enquiry.
Sources and review
- FCA: responsible lending
- FCA: mortgage advice and suitability
- MoneyHelper: consolidation risks
- SRA: identity and source-of-funds checks
- ICO: health and criminal-offence information
Last reviewed: . This article is subject to periodic review. Information and lender criteria may change. General information only; this is not a personal recommendation.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report