

Important information: Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
An inherited deposit and previous County Court Judgments (CCJs) or defaults raise separate mortgage questions. The source and availability of funds, credit history, affordability and the property all require consideration.
Inherited money may be accepted as a deposit, subject to the lender’s requirements and the checks carried out by the legal professional handling the purchase. However, receiving an inheritance does not remove previous credit issues or establish that a mortgage application will be accepted.
This guide explains the information that may be relevant. It cannot establish your eligibility, available borrowing amount or suitable mortgage options.
Inherited deposit: can inherited money be used as a mortgage deposit?
A lender may accept inherited funds as some or all of a deposit where its requirements are met. The funds need to belong to the applicant, be available for the transaction and have an adequately evidenced source.
A direct inheritance is different from money borrowed against an expected inheritance. It is also different from a gift made by another person who has inherited money. Those arrangements may involve different checks and lender policies.
Being named as a beneficiary does not necessarily mean the money is ready to use. The estate may still be under administration, and the amount or timing of a distribution may not yet be confirmed.
The lender and the legal professional handling the purchase will need to understand the actual arrangement rather than relying on an estimate of what you expect to receive.
What evidence of the inheritance may be required?
The documents needed depend on the estate, the payment route and the requirements of the firms carrying out the checks. Relevant evidence may include:
- A letter from the executor, estate administrator or solicitor confirming your entitlement and the distribution.
- Relevant estate accounts or distribution statements.
- A grant of probate, letters of administration or equivalent documents, where applicable.
- Relevant parts of a will, where needed to explain the entitlement.
- Bank statements showing the payment from the estate and any subsequent transfers.
- Evidence of a sale if the inherited asset was sold to produce the deposit funds.
Not every inheritance requires every document listed. Probate procedures and terminology also differ across the UK, and some estates can be administered without a grant.
A bank statement showing that money is available may not, by itself, explain its origin. Holding funds in a UK bank account does not replace source-of-funds checks.
The lender and the legal professional may ask different questions or request additional evidence. Acceptance of the documents by one does not automatically satisfy the other’s requirements.
What if the estate has not finished distributing the money?
An anticipated inheritance should not be treated as an available deposit simply because a distribution is expected. Estate debts, expenses, disputes or other administration matters may affect the amount received or the timing.
If an interim distribution has been made, evidence may be needed to explain the payment and whether the funds are available for the purchase. The relevant firms will decide what confirmation they require.
There is no universal period for which inherited money must sit in a bank account before a mortgage application. Equally, receiving the money shortly before a purchase does not guarantee that all checks can be completed in time.
Questions about entitlement, restrictions or estate administration should be directed to the executor, administrator or an appropriate legal adviser.
How might a lender assess previous CCJs or defaults?
The lender assesses credit history separately from the source of the deposit. Relevant details may include:
- Whether the issue is a default, a CCJ or another type of credit problem.
- The date, amount and number of recorded issues.
- Whether amounts remain outstanding or have been paid.
- Any subsequent missed payments or other credit problems.
- Current debts, repayment arrangements and information requested in the application.
A CCJ is a court judgment; a default recorded on a credit report is not the same thing. Lenders may have different policies for each.
Some circumstances will fall outside a lender’s criteria regardless of the deposit available. An older or paid issue does not automatically meet those criteria, and a consumer credit score is not a mortgage lending decision.
CCJs are part of the court system in England and Wales. Court procedures and terminology differ in Scotland and Northern Ireland.
Does receiving an inheritance remove credit records?
No. Receiving an inheritance does not change the accuracy or reporting period of an existing default or CCJ.
A default generally remains on a credit report for six years from the original default date, whether or not the debt is subsequently paid. Paying it does not restart that reporting period.
For a CCJ in England and Wales, paying the full judgment within one month allows you to apply for its removal from the register. If paid in full after that period, it can be marked as satisfied but normally remains on the register for six years from the judgment date.
A record disappearing from a credit report does not, by itself, establish that an underlying debt has been cancelled or that a mortgage will be available. Application questions must still be answered accurately, including questions about earlier events where asked.
Does a larger inherited deposit overcome lending restrictions?
A deposit affects how much you need to borrow and the loan-to-value ratio. Loan-to-value compares the mortgage amount with the property value accepted by the lender.
However, a lower loan-to-value ratio does not override affordability checks, credit policies or property requirements. It also does not guarantee acceptance or a particular interest rate.
There is no standard deposit percentage for an applicant with CCJs or defaults. Requirements vary by lender, product and circumstances.
Money needed for legal fees, applicable property taxes and other purchase costs must also be considered. The whole inheritance may not be available to use as the deposit.
How is affordability assessed?
An inheritance used as a deposit is capital. It should not automatically be treated as recurring income available to meet monthly mortgage repayments.
A lender will assess the income it accepts alongside expenditure, existing commitments and the proposed mortgage. It may also consider foreseeable changes and whether repayments would remain affordable under its assessment requirements.
Borrowing less can change the proposed repayments, but it does not establish that they are affordable. The mortgage term, repayment method and interest rate also affect the calculation.
An outstanding debt or repayment arrangement may be relevant to expenditure. A satisfied CCJ remains relevant to credit history while recorded, but it should not be described as an ongoing monthly payment where no payment obligation remains.
Should inherited money be used to repay debts first?
There is no general answer that is suitable for every applicant. Using inherited money to repay a debt changes the funds available for the deposit and other costs. It does not guarantee that a lender will accept a subsequent mortgage application.
Decisions about court judgments, settlement offers, existing repayment arrangements or insolvency require consideration of the actual obligations. If you are subject to an insolvency or formal debt arrangement, receiving an inheritance may also create reporting or payment obligations under its rules or terms.
Mortgage Bridge does not advise you to allocate an inheritance between debts, a deposit or other uses. A mortgage adviser can discuss mortgage implications within the scope of their service, while an appropriate debt or legal adviser can explain debt and legal obligations.
If you are struggling with debts, free, independent help is available through MoneyHelper’s debt advice locator.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Illustration: why a deposit percentage is not an approval indication
Suppose an applicant has received £60,000 and is considering a property costing £240,000. If the full £60,000 were available as the deposit, the proposed borrowing would be £180,000, equivalent to 75% of the purchase price.
That calculation does not establish the lender’s valuation, the funds available after purchase costs, or whether the mortgage meets affordability and credit criteria.
If the applicant also has a previous CCJ and a default, the lender would need the relevant details and would apply its own policy. Evidence of the inheritance would be checked separately.
This is an arithmetic illustration only. It does not indicate that the application would be accepted or that a particular mortgage or interest rate would be available.
What if the inheritance comes from overseas or through another person?
An overseas estate may involve additional documents, translations, currency conversion records or checks relating to the countries and organisations involved. Requirements vary, and acceptance should not be assumed.
If another beneficiary receives an inheritance and then gives money to you, that is a separate gift rather than your direct inheritance. The lender and legal professional may need evidence of the donor’s source of funds, the gift and any conditions attached.
Any expectation of repayment, ownership rights or another interest in the property must be disclosed. Moving money through another account does not remove the need to explain its origin.
Are buy-to-let applications assessed differently?
Buy-to-let applications have their own requirements, which may include rental income assessments, landlord circumstances, personal income, property criteria and credit history.
An inherited deposit does not remove those checks. There is no single deposit requirement or rental assessment that applies to every buy-to-let lender.
The regulatory position also depends on the arrangement. An adviser should explain the scope of their service and the protections applicable to any proposed borrowing.
Frequently Asked Questions
Can an inheritance provide the whole mortgage deposit?
It may provide the whole deposit if the lender accepts the source and the funds are available and adequately evidenced. Purchase costs and all other lending requirements still need to be considered.
Does an inherited deposit override a lender’s CCJ or default policy?
No. The lender assesses credit history separately from the deposit source. An application can fall outside its credit or affordability criteria even where a substantial deposit is available.
Must inherited funds stay in a bank account for a set period?
There is no universal holding period. The lender and legal professional will apply their own evidence requirements. A bank balance alone may not establish where the money came from.
Does paying a default or CCJ remove it immediately?
Not usually. A default generally remains for six years from its original date. In England and Wales, a CCJ paid in full within one month can be removed from the register through the appropriate process. If paid later, it can be marked satisfied but normally remains for six years from the judgment date.
Is inherited money treated as income for mortgage repayments?
An inheritance used as a deposit is capital and should not automatically be treated as recurring income. The lender separately assesses accepted income, expenditure and the proposed mortgage repayments.
How Mortgage Bridge can help
Mortgage Bridge provides general information and administrative support and passes mortgage enquiries to advisers acting through an FCA-authorised and regulated network. We do not recommend a mortgage, assess suitability or confirm that an application will be accepted.
The receiving adviser can discuss your circumstances, explain the scope of their service and any applicable fees, and consider whether there are options they can discuss with you. Any lending decision rests with the lender.
Mortgage Bridge has commercial relationships with receiving firms. When an introduced case completes, we receive a percentage of the commission earned by the adviser. We therefore have a financial interest in completed introductions.
You can read more about our role in our About Us page, Terms and Conditions and Privacy Policy.
This guide provides general information only. It is not mortgage, debt or legal advice and does not establish your eligibility for a mortgage.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
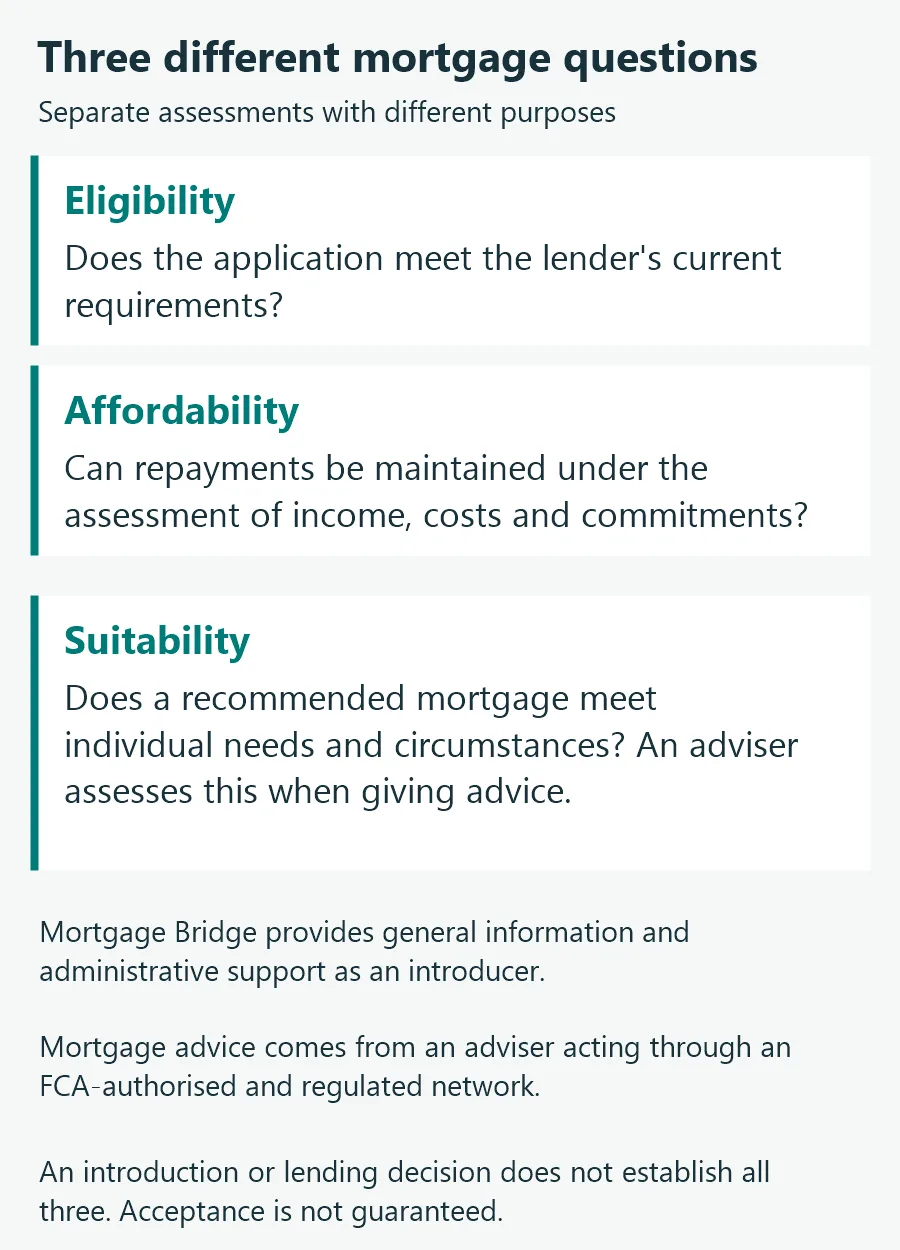
Eligibility concerns a lender’s current requirements. Affordability concerns whether repayments can be maintained, taking account of relevant income, expenditure and commitments. Suitability concerns whether a recommended mortgage meets individual needs and circumstances and is assessed when an adviser acting through an FCA-authorised and regulated network provides mortgage advice. Meeting one assessment does not establish the others. Mortgage Bridge does not carry out these assessments.
Costs and independent debt support
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, using savings or taking additional credit to obtain a mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Referral disclosure
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. An introduction does not guarantee acceptance or completion.
Read about us, our terms and conditions and our privacy policy.
Sources and review
- FCA Handbook: responsible lending
- FCA Handbook: mortgage advice and suitability
- TransUnion: account information and reporting
- ICO: credit records and accuracy
- MoneyHelper: consolidation risks
- GOV.UK: CCJ payment and reporting rules
- SRA: identity and source-of-funds evidence
- Financial Ombudsman Service: valuations and surveys
Last reviewed: . This article is subject to periodic review. Information and lender criteria may change. General information only; this is not a personal recommendation.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report