
Important information: Mortgage Bridge acts as a mortgage introducer and provides general information and administrative support. This guide does not constitute regulated mortgage advice, legal advice or a recommendation. Any regulated mortgage advice is provided separately by an adviser acting through a network authorised and regulated by the Financial Conduct Authority (FCA), following an assessment of your individual circumstances.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Previous legal or financial issues may raise questions during a mortgage application or property transaction. This guide considers a previous investigation connected with the Proceeds of Crime Act 2002 (POCA), without treating an investigation as proof of wrongdoing.
An investigation does not itself establish wrongdoing. Equally, an investigation ending does not establish mortgage eligibility or confirm that every question about a proposed transaction has been resolved.
The outcome of any mortgage application will depend on individual circumstances, supporting evidence, affordability and the specific criteria of the lender approached. Acceptance is not guaranteed.
Previous legal or financial issues: what does the investigation outcome mean for an application?
There is no single mortgage rule covering every previous investigation.
Descriptions such as “cleared” can refer to different circumstances. An investigation ending without further action, proceedings ending without a conviction and a court making a particular order are not necessarily interchangeable.
An adviser, lender or legal professional may need to understand the relevant facts and documents where these are necessary for their work. They apply their own responsibilities and assessment processes.
This guide cannot determine the legal effect of an investigation outcome or whether particular funds or assets can be used in a property transaction. Those questions may require advice from a solicitor.
How a lender may assess the circumstances
A lender may consider information relevant to its lending criteria, affordability assessment and financial-crime checks.
Depending on the application, relevant information may include:
-
Income and employment or trading evidence.
-
Existing debts and financial commitments.
-
Credit history.
-
The source of the deposit and other transaction funds.
-
The property and proposed borrowing.
-
Relevant legal documents or restrictions affecting the transaction.
These are examples, not a standard checklist applying to every applicant or lender.
An explanation or document confirming an investigation’s outcome does not require a lender to accept an application. Lenders may reach different decisions, and providing additional information does not guarantee acceptance.
Source of funds and source of wealth
A property transaction may involve checks on where money comes from.
“Source of funds” concerns the money used for the particular transaction. “Source of wealth” concerns how a person accumulated their wider wealth. The checks and evidence required depend on the firm’s responsibilities and assessment of the transaction.
For example, evidence may relate to savings, employment income, a property sale, inheritance or a gift. A bank statement showing that money is available does not necessarily establish its underlying source.
The solicitor or conveyancer handling a purchase may carry out checks separately from the lender. A mortgage decision does not replace the legal professional’s checks or confirm that they can complete the transaction.
The Solicitors Regulation Authority explains these checks in its consumer guidance on anti-money laundering checks.
What if funds or assets were affected by legal proceedings?
If funds, accounts or assets were subject to an order or restriction, their current legal position may be relevant to the transaction.
The end of an investigation should not be assumed to remove every restriction or resolve questions about ownership or use of funds.
A solicitor can explain the effect of relevant documents or orders. Mortgage Bridge does not interpret court orders, assess the legality of funds or provide advice about POCA proceedings.
Credit history and other checks
A credit report is not a complete record of every legal, financial or compliance issue that could be relevant to a transaction.
The presence or absence of information on a credit report should not be treated as confirmation that a lender or legal professional has no further questions.
Related missed payments, judgments or other recorded credit events may be relevant to a lender’s assessment. Their treatment depends on the lender’s criteria and the applicant’s circumstances.
This guide does not predict what a particular firm will discover, request or decide.
Affordability and deposit requirements
There is no standard deposit percentage or borrowing limit for someone who has been involved in a previous investigation.
Affordability may depend on the income a lender accepts, expenditure, existing commitments and its assessment method. Deposit requirements depend on the lender, product, property and individual circumstances.
A larger deposit does not resolve questions about the source or legal availability of funds. It also does not override a lender’s criteria or guarantee acceptance.
Being able to explain an investigation’s outcome does not establish how much a lender will offer or which terms may be available.
Buy-to-let applications
Buy-to-let enquiries involve their own lending and property requirements. Depending on the lender and transaction, these may include rental-income assessment, personal financial circumstances, existing borrowing, deposit and property characteristics.
A previous investigation does not establish a particular buy-to-let outcome. Source-of-funds and relevant legal checks remain separate considerations.
This guide does not recommend property investment or establish that a buy-to-let mortgage is suitable or available.
An illustrative scenario
Consider an applicant whose previous financial investigation has ended and who is now considering a property purchase.
The applicant has evidence of income and money intended for a deposit. An adviser or legal professional may need to establish what information is relevant to their role, including the origin of the deposit and whether any legal restrictions remain.
The lender would apply its own criteria and assessment. The solicitor or conveyancer would separately consider the legal and compliance requirements of the transaction.
These facts are not enough to predict acceptance, deposit requirements, interest rates, processing times or whether the transaction can complete.
This is an illustrative example only. It is not a customer testimonial, a completed mortgage case or evidence that another applicant will receive a similar outcome.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Documents and enquiries
Where relevant, an adviser, lender or solicitor may request evidence of income, deposit sources, transactions or the legal position.
The receiving professional should explain what they need and how to provide it securely. Supplying documents does not guarantee acceptance or completion.
Information about criminal allegations, investigations and proceedings receives additional protection under data-protection law. Mortgage Bridge does not request detailed criminal-offence information or investigation documents through its initial enquiry service.
Please do not upload investigation reports, criminal-offence records or court documents concerning such matters to Mortgage Bridge. If an adviser firm operating within an FCA-authorised and regulated network or solicitor needs them, use the secure process that firm specifies.
Disclosure and legal questions
Application questions should be answered accurately. This guide does not determine whether a particular past event must be disclosed in response to a particular question.
If you are unsure what a question covers or what information can lawfully be shared, seek clarification from the receiving firm and, where necessary, advice from a solicitor.
The purpose of providing information is to enable the relevant professional to carry out their assessment. An explanation is not a way to bypass lending criteria or legal checks.
Timescales and possible outcomes
A firm may request further information or refer a matter for additional review. The extent and timing of that work depend on the circumstances and the firm’s process.
There is no guaranteed review period, mortgage decision or completion date.
A lender or professional firm may be unable to proceed. The fact that another applicant or another firm previously proceeded does not establish what will happen in your circumstances.
How Mortgage Bridge can help
Mortgage Bridge provides general mortgage information, administrative enquiry support and adviser introductions where appropriate.
We do not assess mortgage suitability, determine eligibility, recommend lenders or products, provide regulated mortgage advice, make lending decisions or provide legal advice.
Any regulated mortgage advice is provided separately through an FCA-authorised and regulated network. An introduction does not guarantee that the firm will accept or progress an enquiry.
Mortgage Bridge has commercial referral arrangements and receives a percentage of the adviser’s commission when an introduced case completes.
See About Us, our Terms and Conditions and Privacy Policy for introduction, payment and information-sharing arrangements.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
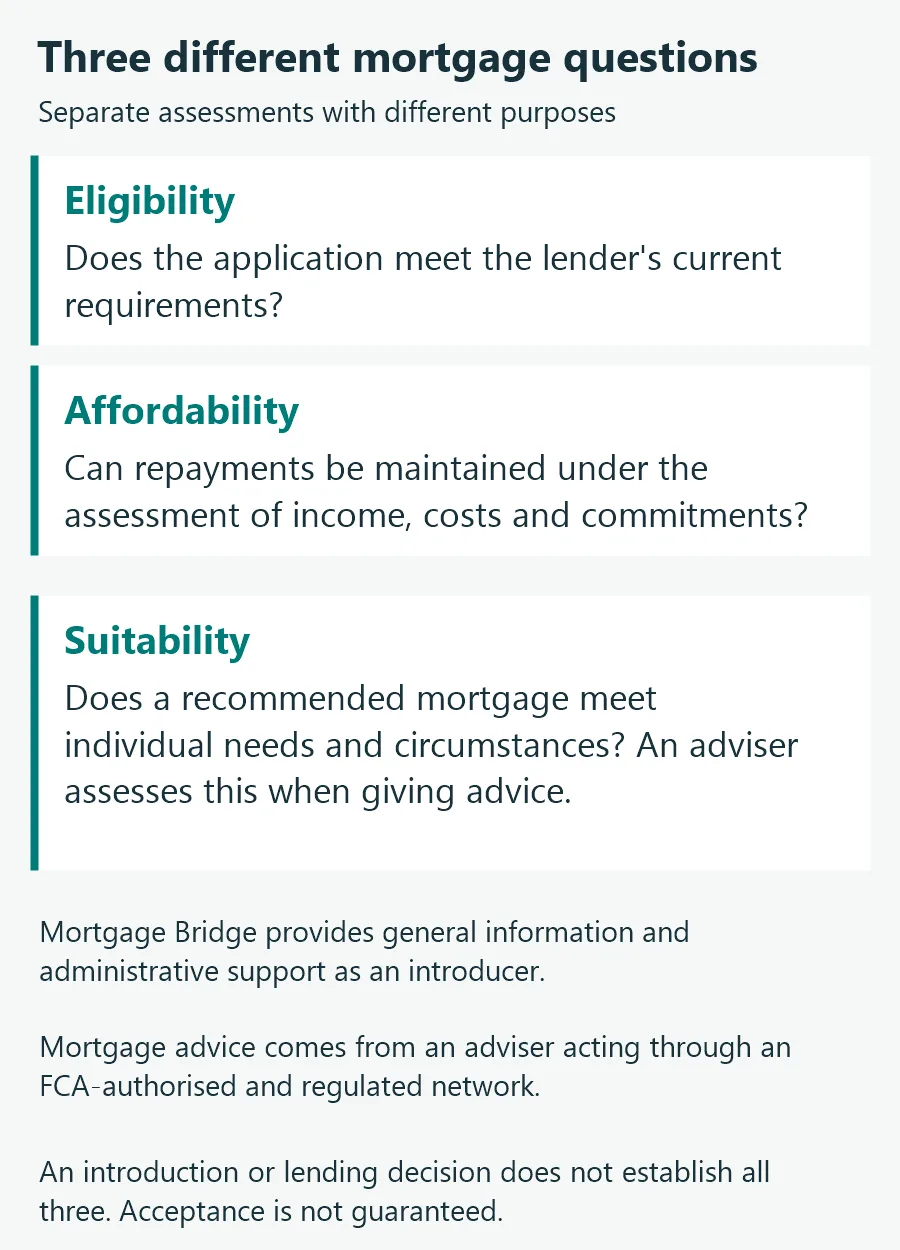
Eligibility concerns the lender’s current requirements. Affordability concerns whether repayments can be maintained, taking account of relevant income, expenditure and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances and is assessed when an adviser acting through an FCA-authorised and regulated network provides mortgage advice. Passing one assessment does not establish the others. Mortgage Bridge does not carry out these assessments or provide mortgage or debt advice.
Free independent debt support
Free, independent debt advice is available through MoneyHelper’s debt advice locator.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Frequently asked questions
Does an investigation ending mean a mortgage will be available?
No. An investigation’s outcome does not establish mortgage eligibility. Availability depends on individual circumstances, supporting evidence, affordability, lender criteria and any relevant legal or compliance requirements.
Do all lenders approach previous investigations in the same way?
No single approach should be assumed. A lender applies its own criteria and relevant checks. This guide does not identify a lender that will accept a particular situation.
Will the investigation appear on a credit report?
A credit report should not be treated as a complete record of an investigation or all information relevant to a transaction. Related financial events may be recorded, and firms may carry out checks beyond a credit search.
Will extra documents be required?
They may be, depending on the circumstances and the firm’s requirements. There is no universal document list. Providing evidence does not guarantee a favourable decision.
Would a larger deposit resolve the issue?
Not necessarily. Deposit size does not resolve questions about the origin, ownership or legal availability of funds, and does not guarantee mortgage acceptance.
Can Mortgage Bridge review investigation documents?
Mortgage Bridge does not provide legal or regulated mortgage advice and does not request detailed investigation or criminal-offence documents through its initial enquiry service. Where such documents are needed, the adviser firm operating within an FCA-authorised and regulated network or solicitor should explain their own secure submission process.
Can a buy-to-let application be considered?
That depends on the lender, transaction and individual circumstances. Neither a previous investigation ending nor the proposed rental income establishes that a mortgage will be available.
Mortgage Bridge is a mortgage introducer and does not provide regulated mortgage advice or legal advice.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Information about lender practices may change. Requirements should be checked at the time of an enquiry.
Sources and review
- FCA: responsible lending
- FCA: mortgage advice and suitability
- MoneyHelper: consolidation risks
- SRA: identity and source-of-funds checks
- ICO: health and criminal-offence information
Last reviewed: . This article is subject to periodic review. Information and lender criteria may change. General information only; this is not a personal recommendation.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report