
Mortgage Bridge provides general information and administrative support as a mortgage introducer. It does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Securing previously unsecured debts against a home increases the risk to the home. Lower monthly payments do not necessarily mean lower total costs. Longer repayment terms and fees can increase the total amount repaid.
Mortgage address history can contain mismatches for different reasons. Current and previous details need accurate explanation without assuming an inconsistency proves fraud.
Credit records and a consumer credit score are different from a lender’s decision. Account history, identity information and public records can be considered alongside income, expenditure and the property.
This guide explains the limits of credit information without setting an approval score, a waiting period or a credit-repair strategy. Correcting an inaccuracy is different from removing accurate history, and neither establishes a mortgage outcome.
Can address-history problems cause a mortgage decline?
Inconsistent or incomplete address details can lead to verification questions and may affect an application. A request for clarification is not the same as a final decline, and a mismatch alone does not establish fraud. Identify the record in question before assuming the reason for the lender’s decision.
Address history: build a dated timeline
List the addresses requested by the application, the dates you actually lived there and the full flat or house details. Keep a correspondence address separate from a residential address. Do not substitute a family address for where you lived simply to remove a gap.
The period requested depends on the lender and form. If you cannot recall a date, check existing records or ask how an approximate date should be recorded rather than inventing precision. Study, overseas residence, temporary accommodation and overlapping tenancies may need explanation.
Address mismatches: distinguish the records
A bank statement may retain a previous correspondence address; a credit report may link earlier addresses; an application asks for the history specified on its form. These records can differ without describing the same error.
- Formatting: check flat number, building name and postcode against the original record.
- Timing: distinguish a genuine previous address from an out-of-date current one.
- Missing history: explain the actual period and circumstances.
- An unfamiliar address: query its origin with the organisation holding it.
Do not edit a bank statement to make it match. Ask the issuer about an inaccurate document.
How to challenge an incorrect address on a credit report
Experian explains how addresses help match credit information and how to query missing or incorrect addresses. A previous address is not automatically an error, and living at an address does not by itself link you financially to everyone who lived there.
Keep the disputed record, the correction request and any response together. Tell the adviser or lender that a correction is pending rather than assuming it is already reflected in every system. Correcting information improves accuracy; it does not guarantee mortgage acceptance.
If the lender’s concern is instead about transactions, income or commitments, use the separate bank-statement guide. Address verification and financial affordability answer different questions.
What bank statements can show
Bank statements can help connect declared income, actual receipts, regular spending and transfers between accounts. They may also identify commitments not obvious from a payslip. The requested period, account types and acceptable format depend on the lender and the application. A statement is evidence within an assessment, not a standalone approval or rejection test.
A transfer into an account does not automatically establish its original source. Likewise, a single unfamiliar transaction needs context before its meaning is known. There is no universal spending limit, overdraft allowance or list of purchases that guarantees acceptance. Complete, genuine records matter; moving spending elsewhere or editing a statement would not provide an accurate account of the financial position.
How affordability differs from a headline income figure
Income establishes only part of a mortgage assessment. The lender also considers expenditure, existing financial commitments and relevant foreseeable changes under the rules that apply to the loan. Gross salary, take-home pay and the income a lender recognises are different figures. An online borrowing estimate cannot establish which amount will be accepted.
An income multiple can be a limit within a lender’s policy without being the amount it will offer. Property value, credit requirements and the requested term can impose separate restrictions. Two applicants earning the same amount can receive different decisions because their costs and circumstances differ. This guide does not set a universal salary threshold or promise a particular advance.
Documents serve different verification purposes
Identity and address evidence identifies the applicant; income and account records help explain finances; deposit documents address purchase funds. Property and legal papers concern the security and transaction. A record supplied for one purpose may not answer a different question. The lender and conveyancer can request different information even in the same purchase.
The relevant document period and format depend on the case. A generic checklist cannot guarantee completeness, and electronic verification may affect what is requested. Missing, inconsistent or outdated information can lead to questions, but providing a complete set does not establish acceptance. The lender still applies its criteria, while the conveyancer carries out the legal work within the terms of the instruction.
Need help with your mortgage?
What happens after a mortgage enquiry?
This is an initial enquiry for administrative support and an adviser introduction where appropriate. It is not a mortgage application or an eligibility assessment. Any mortgage advice comes separately from an adviser acting through an FCA-authorised and regulated network. The receiving firm explains its service, fees and information requirements.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes. Acceptance is not guaranteed.
Ask about an adviser introduction
Send details of your enquiry for administrative support and an adviser introduction where appropriate. Mortgage Bridge does not provide mortgage or debt advice, assess eligibility, affordability or suitability, or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Make a mortgage enquiryNo obligation. Mortgage Bridge acts as a mortgage introducer.
Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Your home may be repossessed if you do not keep up repayments on your mortgage.
A decline, referral and request for evidence are different
A declined application means the lender has not agreed the requested borrowing on the information and terms assessed. A referral for review or a request for another document is not necessarily a final refusal. The actual message and stage need to be established rather than inferred from a delay or from a generic article title.
Reasons can concern income, affordability, credit, identity, the property or another requirement. A reason given for one application does not establish the outcome at another lender. Correcting information or providing an explanation may resolve a factual question without guaranteeing approval. This guide does not promise a lender that will accept a declined case or recommend repeated applications as a solution.
Eligibility, affordability and suitability
Visual explanation: eligibility, affordability and suitability
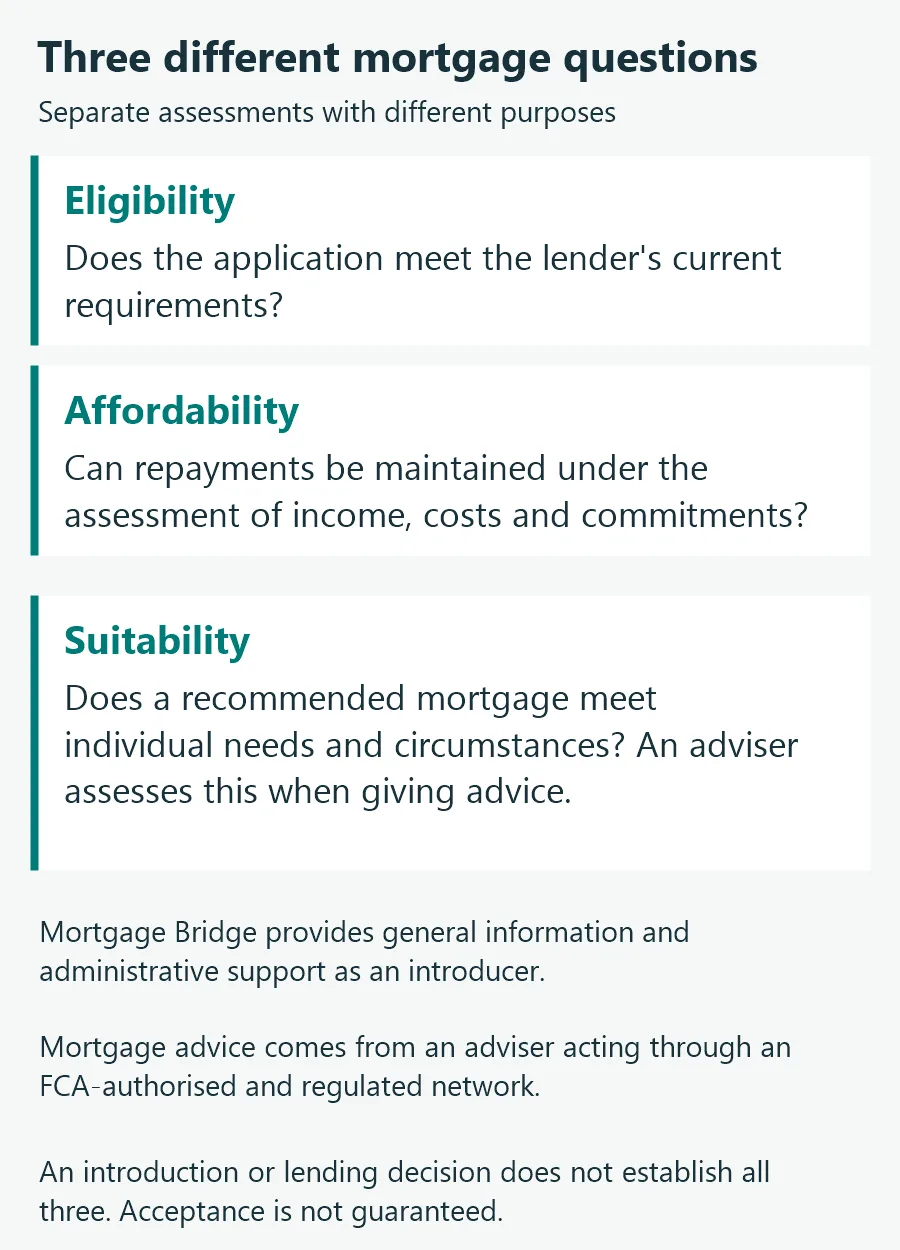
Eligibility means meeting a lender’s current requirements. Affordability concerns maintaining payments under the relevant assessment of income, costs and commitments. Suitability concerns whether a recommended mortgage meets an individual’s needs and circumstances; an adviser assesses this when giving advice. An initial check, valuation or lender approval does not establish all three.
The outcome depends on individual circumstances, supporting evidence, affordability, the property and lender criteria. Acceptance is not guaranteed.
Debt support and Mortgage Bridge’s role
Free, independent debt advice is available through MoneyHelper’s debt advice locator. This guide does not recommend changing debt repayments, taking new credit or using savings to obtain a mortgage.
Any review by Mortgage Bridge is administrative only. An introduction is not a lending decision or a personal recommendation. Mortgage Bridge has commercial relationships with receiving firms and receives a percentage of the adviser’s commission when an introduced case completes.
Read about us, our terms and conditions and our privacy policy.
Frequently asked questions
How many years of address history do mortgage lenders need?
Use the period requested by the particular lender and application form. There is no single period established by this guide for every lender. Ask how to record gaps, overseas residence or uncertain dates accurately.
Does a different address on my bank statement automatically mean a mortgage refusal?
No universal automatic outcome follows from that difference alone. It may require explanation or correction by the issuer. The lender decides what verification is needed and assesses the full application.
Does meeting eligibility criteria establish affordability or suitability?
No. Eligibility concerns lender requirements; affordability concerns the ability to maintain payments; suitability concerns the individual needs assessed when an adviser makes a recommendation. These are separate questions.
Does Mortgage Bridge give personal mortgage or debt advice?
No. Mortgage Bridge provides general information and administrative support as an introducer. It does not assess eligibility, affordability or suitability or recommend products. Mortgage advice comes from an adviser acting through an FCA-authorised and regulated network.
Sources and review
- ICO: credit records, checks and inaccurate information
- FCA: responsible lending and affordability
- Halifax: mortgage criteria (one lender’s policy)
- MoneyHelper: secured debt and consolidation costs
- MoneyHelper: applying for a mortgage
- Experian: soft and hard credit searches
- Nationwide: affordability criteria (one lender’s policy)
- SRA: identity and source-of-funds checks
- MoneyHelper: declined mortgage applications
- FCA: advised mortgage sales and suitability
Lender pages illustrate individual policies, not universal requirements or recommendations.
Last reviewed: . This article is subject to periodic review. Information, rules and lender criteria may change.
Check your credit in detail
View your full credit report
See your credit information from all three major credit reference agencies with Checkmyfile. Try it free, then it becomes a paid monthly subscription. You can cancel online anytime.
Check your credit report